Yes, you usually can. A pre-existing condition does not automatically mean a superannuation insurance claim (TPD) cannot be made.
What decides it is which cover you held.
- Full cover covers pre-existing and new conditions alike.
- Limited cover pays only for an illness or injury that first arose on or after your cover started.
This article will explain the differences and guide you through everything you need to know before making your claim.
Understanding Pre-Existing Conditions, Limited Cover and Full Cover
Three different things get muddled here, and it can cause a lot of confusion.
- A pre-existing condition is a fact about your health history.
- Limited cover is a restriction on what your policy pays for, most commonly a pre-existing health condition.
- Full cover is the absence of that restriction, meaning that, for the most part, pre-existing health conditions are included.
What 'pre-existing condition' means in a super policy
A pre-existing condition is a health problem you already had before your cover started. Each fund sets its own definition, so the exact test differs. Hostplus, for example, counts any injury, sickness, condition or related symptom that you, or a reasonable person in your position, were aware of or should have been aware of, or had (or would have had) a medical consultation for, in the two years before your cover started or restarted.
Under a definition like that, what counts is what you knew and what care you sought in the look-back window, not only when a doctor wrote the diagnosis down. Read the definition in your own fund’s guide, because the look-back period and the wording are not the same everywhere.
The test is when the illness first appeared, not when a doctor wrote the diagnosis down. How recently you were treated does not decide it either, so depression treated five years ago can still count as pre-existing.
A pre-existing condition might not mean your claim will fail, though. It all depends on which type of cover you were on: limited or full.
What 'limited cover' actually means
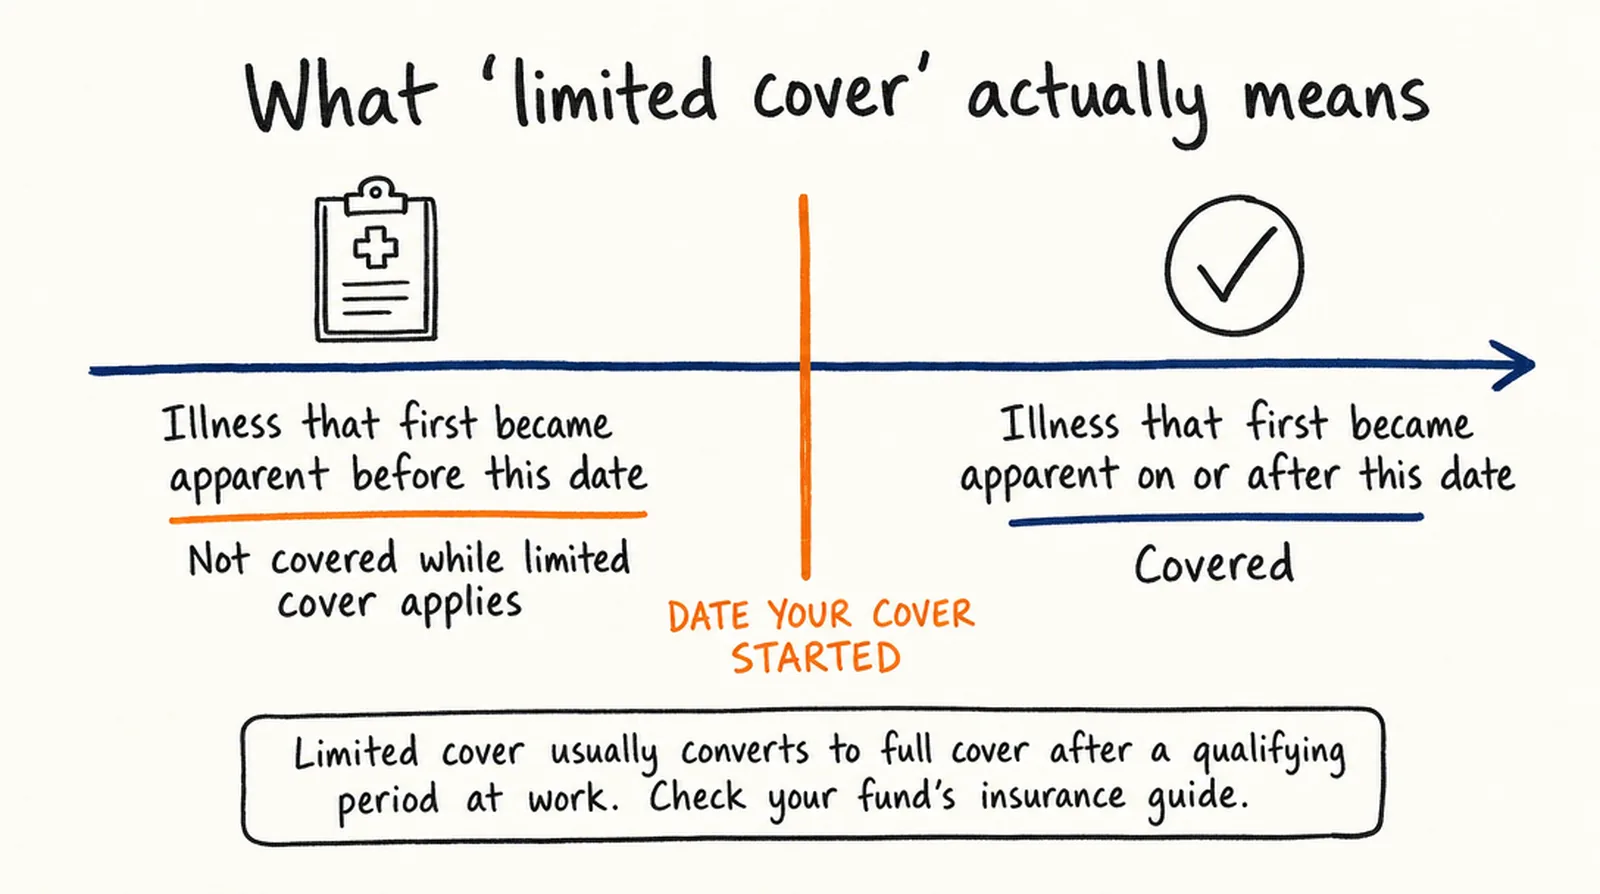
Limited cover is the exclusion of pre-existing medical conditions. It is not a gentler test of disability, and it is not cover with fewer exclusions.
Different funds use different names for limited cover. Hostplus calls it Limited Cover, while Media Super refers to New Events Cover, and legalsuper describes the restriction under Critical Exclusion. You may also see the term Limited Terms Cover.
Despite the different labels, these terms generally describe the same basic restriction: cover is limited to illnesses that first became apparent, or injuries that first occurred, on or after the date your cover started, restarted or increased.
Hostplus’s insurance guide defines Limited Cover in one line: “you are not covered for a Pre-existing Condition”. Media Super states the consequence plainly: ‘If your cover is limited to new events cover and the illness or injury that led to the claim isn't a new event, your claim won’t be paid’. Check your own insurance guide for the terminology your fund uses.
Further detail on section 47 is provided in the Legal Framework section below.
When ‘limited cover’ is applied, and when it’s lifted
Limited cover is usually an initial condition rather than a permanent one.
The common triggers are:
- A first employer contribution being late
- Not being at work when your cover began
- Cover reinstated after having ended at some point
- Or, extra cover given without underwriting
Aware Super's Key Facts Sheet shows how ‘a first employer contribution being late’ can affect its Basic Cover. The document confirms that ‘superannuation guarantee contribution must be received within six months of ‘eligibility date’, otherwise, Limited Cover will apply’.
In most cases, limited cover converts to full cover after a qualifying period. Hostplus, Cbus, Media Super, and legalsuper's personal members all require about 24 months (legalsuper's employer-sponsored default cover is 12 months), plus a continuous period at work of either 10 or 30 consecutive days. In many cases, 24 months is common, but the period and the at-work trigger both vary, so it’s best not to assume a number.
Cbus defines active employment as being gainfully employed and at work on your normal duties, without being restricted by illness or injury. Employer-approved leave counts if you could do those duties. Once converted to full cover, conditions that existed before it started are covered.
Default Cover and Underwritten Cover: The Difference That Decides Everything
Before looking at pre-existing conditions, you need to know how your TPD cover began. Automatic cover and underwritten cover work differently, particularly when an insurer is trying to link your claim to something that happened before your cover started. Let’s take a look in detail.
The practical point: if nobody ever asked you a health question, there’s no answer you could’ve got wrong. Disclosure disputes belong to people who filled in a form. Most Australians hold TPD cover through super without ever having applied for it.
Your Rights and Obligations
When you make a TPD claim, you have rights, but you also have obligations. The important thing is understanding what the law actually requires of you, because those obligations are often narrower than people assume.
What are you entitled to?
- Written reasons. Where a trustee rejects a complaint, ASIC Regulatory Guide 271 requires its internal dispute resolution response to give the reasons, tell you that you can go to AFCA, and provide AFCA's contact details (RG 271.53).
- A response within 45 calendar days. That is the trustee's maximum time allowed for an internal dispute resolution response on a superannuation complaint, other than one about a death benefit distribution (RG 271, Table 2).
- A standard of reasonable care, not perfection. Where you answered health questions, the test is whether you took reasonable care not to make a misrepresentation, not whether your answers were flawless. This protection is granted by the Insurance Contracts Act 1984 (Cth).
- Protection where the form was the problem. An ambiguous question is interpreted according to how a reasonable person would have understood it (section 23). An answer is not a misrepresentation if you gave it honestly and had reasonable grounds for doing so (section 26). A blank or obviously incomplete answer is also not treated as a misrepresentation (sections 27 and 20B(5)). Sections 23 and 26 expressly extend these protections to people joining a superannuation or group life scheme.
What must you do?
- Answer honestly and completely if you are asked. Put down everything you know, including anything you think is minor. You can say you think it is minor.
- Attend reasonable medical examinations, and supply evidence within the timeframe the insurer sets in writing. There is no standard window, so if the date in the letter does not work, ask for an extension in writing.
- Lodge without unnecessary delay. No law sets a deadline for lodging a TPD claim, but if you permanently stopped work because of your condition and you wish to file a complaint concerning the trustee’s decision, AFCA can only consider it within two years of you stopping work (AFCA Rule B.4.1.1).
Common Scenarios and Questions
My fund says I'm on limited cover. Does that mean my claim is finished?
No, not on its own. Three questions still matter. Has your limited cover already converted to full cover, and is the insurer using the right cover start date? When did the illness first become apparent, against that date?
What to do:
- Ask your fund in writing which cover you were on when your condition first became apparent, and to confirm the date your cover started or last increased
- Gather your medical records for the period before that date, because that is the period in dispute
- Check your other super accounts, because each policy has its own start date and its own position on limited cover. ATO online services via myGov shows active, lost and ATO-held accounts. Our guide on finding lost super and TPD cover explains how to chase them up.
I had depression years ago and never mentioned it. Can they reject my claim?
If you were never asked, there is nothing to reject. Default cover is issued without health questions, so there is no answer to get wrong.
If you did answer health questions when you applied, your answers matter. The consequences are still narrower than 'the policy is void'. The Legal Framework section below goes into more detail about what your insurer can and can’t do here.
If a mental health condition is behind your claim, our guide to making a TPD claim for PTSD, depression or anxiety covers what the test asks and what evidence matters.
A work accident made an old back injury much worse. Can I claim?
Yes. A pre-existing injury in your history does not by itself defeat a claim. TPD is assessed as one question: whether you meet your policy's definition of total and permanent disablement (TPD). Inside your super, that is generally an 'any occupation' test, which the Cbus guide phrases as being unlikely ever to do any regular paid work you are reasonably suited to in terms of education, training or experience.
The benefit is a single lump sum. It is not split between an old component and a new one, and there is no partial TPD payment for an aggravation.
A workers' compensation or compulsory third party claim and a TPD claim are separate entitlements, and can generally run alongside each other anywhere in Australia. Scheme rules differ in every state and territory, so get advice on how the two interact where you live.
Legal Framework
Firstly, the Insurance Contracts Act 1984 (Cth) applies to your cover. Section 9 lists the types of contracts the Act does not cover, and superannuation is not among them. Although your super fund's trustee holds the insurance policy, you are the life insured rather than the policy owner. The fact that you are not the policy owner does not prevent the Act from giving you rights under the policy. Section 48A allows you to recover money payable under the contract, while section 13(3) extends the duty of utmost good faith to you. Section 32 also treats your cover as a separate contract that comes into existence when you become a life insured.
Section 47: the limit on pre-existing condition exclusions
This is the provision that matters most in terms of the topic of this article, and it is rarely mentioned. It applies where a claim is made for a loss caused, wholly or partly, by a sickness or disability the person was subject to on any previous occasion.
Where the person insured was not aware of that sickness or disability when the cover was entered into, and a reasonable person in the circumstances could not be expected to have been aware of it, the insurer may not rely on a policy term that limits or excludes its liability by reference to a pre-existing sickness or disability. Or, put simply, you cannot be penalised for a condition you did not know you had and could not reasonably have known about.
Section 29: the three years run against the insurer, not you
Where you did answer health questions and something was missed, section 29 determines what happens next. Most importantly for you, non-disclosure doesn’t automatically void the policy. If the insurer would have offered you the same cover anyway, the missed information does not affect your claim.
If the failure was not fraudulent and the insurer would not have offered cover at all, it can cancel the cover, but only within three years of the cover starting. In other cases, the insurer can only reduce the amount it pays under a given formula set out in section 29.
What the three-year period means
The three-year period outlined above limits what the insurer can do. It is not a deadline for making a TPD claim. The Act does not set a time limit for this. Section 32 also means the relevant date is when you became a life insured, not when the fund first took out its master policy.
What duty applies to you?
Section 21 sets out a duty of disclosure, but it does not generally apply to consumer insurance contracts. For a life insured answering health questions, the relevant test is whether you took reasonable care not to make a misrepresentation, under sections 20B and 27AA(2).
The superannuation rules
The Superannuation Industry (Supervision) Regulations 1994 (Cth) contain another important rule. Regulation 1.03C defines permanent incapacity as ill health that means the trustee is reasonably satisfied you are unlikely to work again in a job for which you are reasonably qualified by education, training or experience.
Since 1 July 2014, regulation 4.07D has required insurance through super to be consistent with the conditions that allow a benefit to be released. In practice, this means a TPD policy cannot provide a benefit where you do not meet the superannuation definition of permanent incapacity.
What this means for your TPD claim
If your TPD cover is through super and started after 1 July 2014, you will generally need to meet an ‘any occupation definition’ rather than an ‘own occupation definition'. Some members with older cover may still be covered by the previous rules.
You can see more about the differences between these definitions in our article ‘Own Occupation' vs. 'Any Occupation': Understanding Your TPD Policy Definition’.
Red Flags and Seeking Legal Advice
Below are some situations in which we’d recommend seeking specialist advice:
- A decline letter cites a pre-existing condition or limited cover without identifying the illness, when it first became apparent, or the cover start date
- The insurer treats the date of your formal diagnosis as the date the illness first became apparent
- You are told limited cover applies and you have suspicions that it has or should have converted to full cover
- The exclusion is being applied to something you did not know about (see information about section 47 above)
- You are asked to sign a form allowing access to all your past medical records, without a time limit
- You hold cover across several funds, or are deciding whether to consolidate accounts while unwell
Common mistakes to avoid:
- Assuming a health condition in your history ends the claim. It usually does not
- Assuming limited cover is less of a problem than a policy exclusion. It is the exclusion
- Assuming you are out of time. There is no statutory deadline for lodging, and no deadline at all on asking the trustee to review a decision
- Consolidating super accounts without checking what cover you are giving up
Seeking legal advice
Disputes often revolve around very subtle elements, such as when a condition first became apparent or the exact wording that has been used on documents that will be submitted, and that evidence is easier to assemble before an insurer has formed a view. Early legal advice is a way to pre-empt such issues, making the process smoother overall.
Key takeaways
Remember these essential points:
- A pre-existing condition does not automatically mean a rejected TPD claim. What matters is which cover applied when your illness first became apparent, or your injury happened.
- Limited cover is the pre-existing exclusion, not a softer version of cover. It pays only for conditions that first arose on or after your cover started. Some funds call it new events cover.
- Limited cover is usually temporary. It commonly converts to full cover after around 24 months plus a continuous period at work, but the period and the trigger vary by fund.
- If you were never asked a health question, disclosure is not your problem. Default cover is issued without underwriting, so limited cover is the thing to check instead.
- An exclusion cannot be used against a condition you did not know about. Under section 47 of the Insurance Contracts Act 1984 (Cth), an insurer cannot rely on a pre-existing condition exclusion where the person insured was unaware of the condition, and could not reasonably have been expected to be aware of it.
Get Help Now
If you’ve been told that a health condition from before your cover started rules you out, it’s almost certainly worth a second look. Most of these decisions come down to a specific date and a definition, and both are open to interpretation.
Smith's Lawyers offers a no-obligation review of your situation with no upfront cost. A member of the team will assess your rights, explain your options and let you know the best course of action.
Contact Smith's Lawyers today:
- Call 1800 960 482 for a free, no-obligation consultation about your situation
- No upfront costs: We operate on a No Win, No Fee, No Catch® basis; you only pay if we secure compensation for you
- Or request a call back: Use the form below to have our experienced team get in touch at a time that’s convenient for you.