Most Australians who hold total and permanent disability (TPD) cover hold it inside their superannuation fund as default cover (i.e., inside super). This likely started automatically.
A stand-alone policy is one you applied for and own yourself (i.e., outside super).
The main differences are:
- the definition of disability used;
- who has to approve the payment; and
- how the money is taxed.
Your annual super statement will tell you which one you have, but this article will help in understanding the differences between them.
Quick Answer Box
Key points:
- With inside super, the standard is generally 'any occupation'. Own occupation cover has not been available for cover starting on or after 1 July 2014.
- A super benefit has to pass two stages: (1) the insurer decides the claim, then (2) the trustee must be satisfied you meet the permanent incapacity condition of release.
- A super benefit can be taxed if you are under 60. A policy that you personally own (outside super) is generally not taxed.
- No law sets a deadline for lodging a TPD claim with your super fund.
Do I have TPD cover in a super or a standalone policy?
The quick test: If you've never applied for the cover or paid the premiums yourself, you probably have default cover through your super fund. If you completed a health questionnaire when applying, it's more likely to be a stand-alone policy.
What’s the biggest difference between these types of policy?
The key difference is what the definition looks at: inside super, whether you can do any job you’re reasonably suited to (‘any occupation’); outside super, whether you can do the job you actually did (‘own occupation’).
What are the key timeframes?
There’s no time limit for lodging a claim with your fund. However, if you permanently stopped work because of your condition, AFCA can only consider a complaint about your fund’s decision if you made the claim within two years of stopping work.
What’s the best action to take first?
Open the insurance section of your latest annual super statement. It shows whether you hold TPD cover and how much it’s worth. Alternatively, find the same details you hold, but for your standalone policy.
Understanding TPD Cover and Where It Sits
TPD insurance pays a lump sum if illness or injury leaves you permanently unable to work.
It sits in one of two places:
- inside a superannuation fund, where the trustee holds the policy and premiums come from your balance
- or, outside super, where you own it
The three definitions insurers use
The definition in your policy decides your claim, so it matters more than the dollar amount. Moneysmart, ASIC's consumer website, describes the three main definitions:
| Definition | What you have to show |
|---|---|
| Own occupation | You cannot work again in the job you were doing. Usually only available outside super. For example, a plumber who can no longer work as a plumber. |
| Any occupation | You cannot work again in any job suited to your education, training or experience. The threshold here is higher, given that many physical injuries wouldn’t stop a person from performing a desk job, for example. |
| Activities of daily living | You cannot do basic self-care tasks such as bathing or dressing without help. This has the highest threshold of all three. |
See also our guides to own and any occupation definitions and the activities of daily living definition.
The Main Differences Between Default Super Cover and a Stand-Alone Policy
Six things change depending on where your cover sits:
- the definition;
- who approves the payment;
- the tax;
- the premiums;
- whether you were health-checked; and
- how much cover you hold.
The definition and the tax are the two that surprise people most when it comes to making a claim.
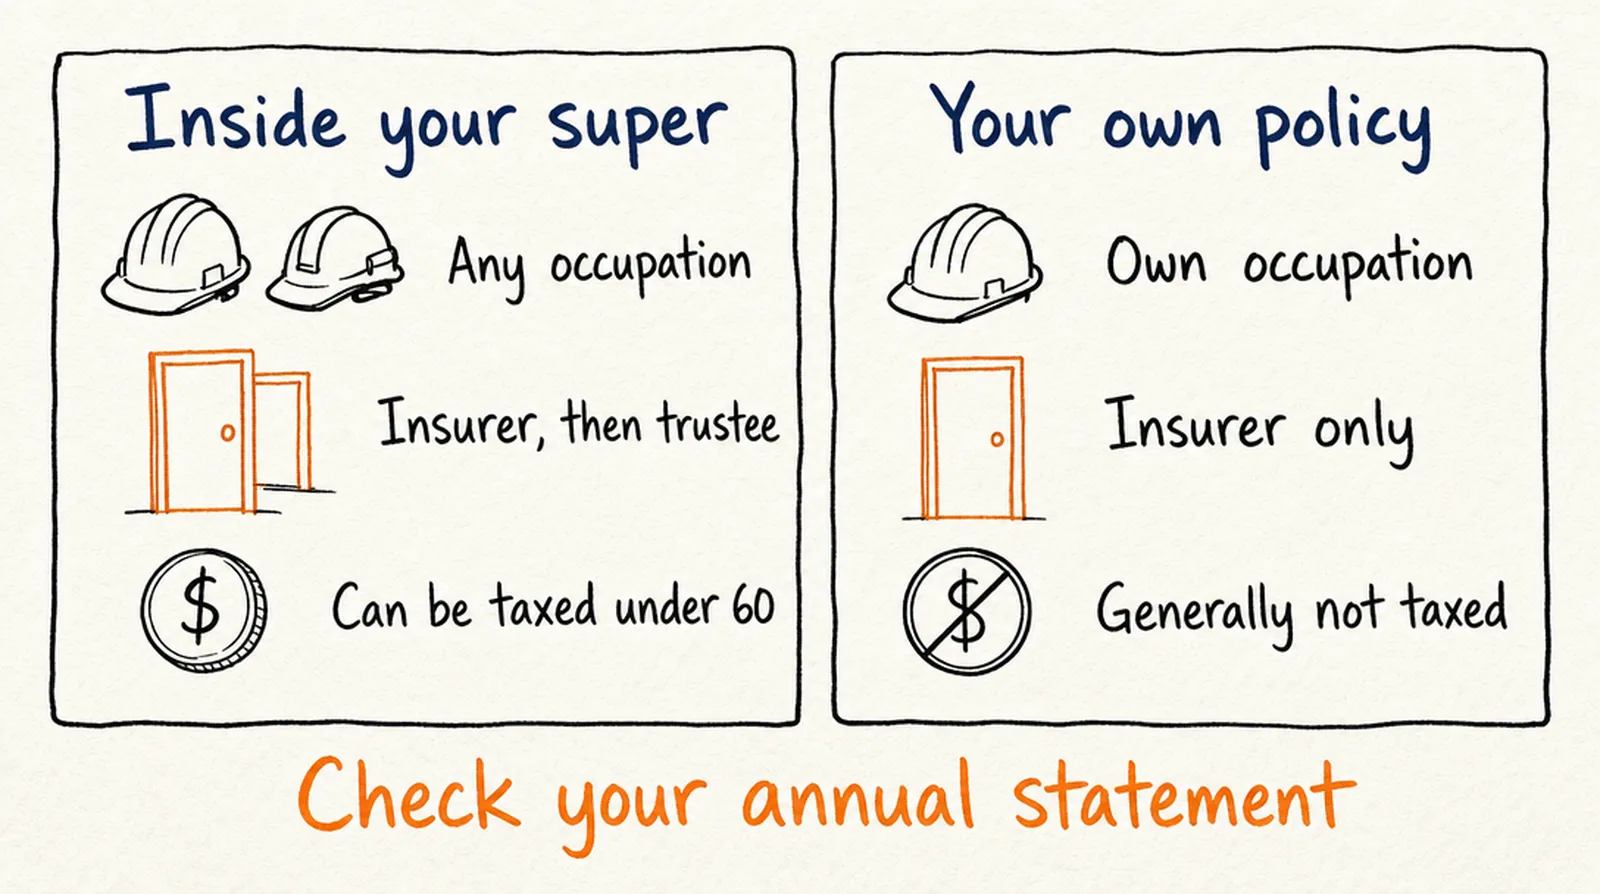
| Inside super (default) | Outside super (stand-alone) | |
|---|---|---|
| Definition | Generally 'any occupation' | 'Own occupation' available |
| Who approves payment | Insurer, then the trustee | Insurer only |
| Tax on the benefit | Can be taxed if the claimant is under 60 | Generally not taxed |
| Premiums come from | Your super balance | Your own money |
| Health questions | Usually none | Yes, individually underwritten |
| Cover amount | Set by the fund, changes with age | Chosen when you apply |
Why own occupation cover is not available inside super
Since 1 July 2014, a trustee cannot provide an insured benefit unless the insured event lines up with a condition of release: death, terminal medical condition, permanent incapacity or temporary incapacity. That is reg 4.07D(2) of the Superannuation Industry (Supervision) Regulations 1994 (Cth).
An own occupation definition can pay out to someone who could still work in another job, so it does not match the permanent incapacity condition of release. That is why funds no longer offer it for cover starting on or after 1 July 2014.
Under reg 4.07D(3)(a), benefits can continue for members who joined a fund before 1 July 2014. If that is you, make sure to find out what definition your cover uses.
Getting paid: super has two stages, whereas a personal policy only has one
Inside super, two separate decisions have to go your way. The insurer decides whether you meet the TPD definition in the policy. The trustee must then be satisfied you meet the permanent incapacity condition of release before the money can leave your super account (Schedule 1 item 103).
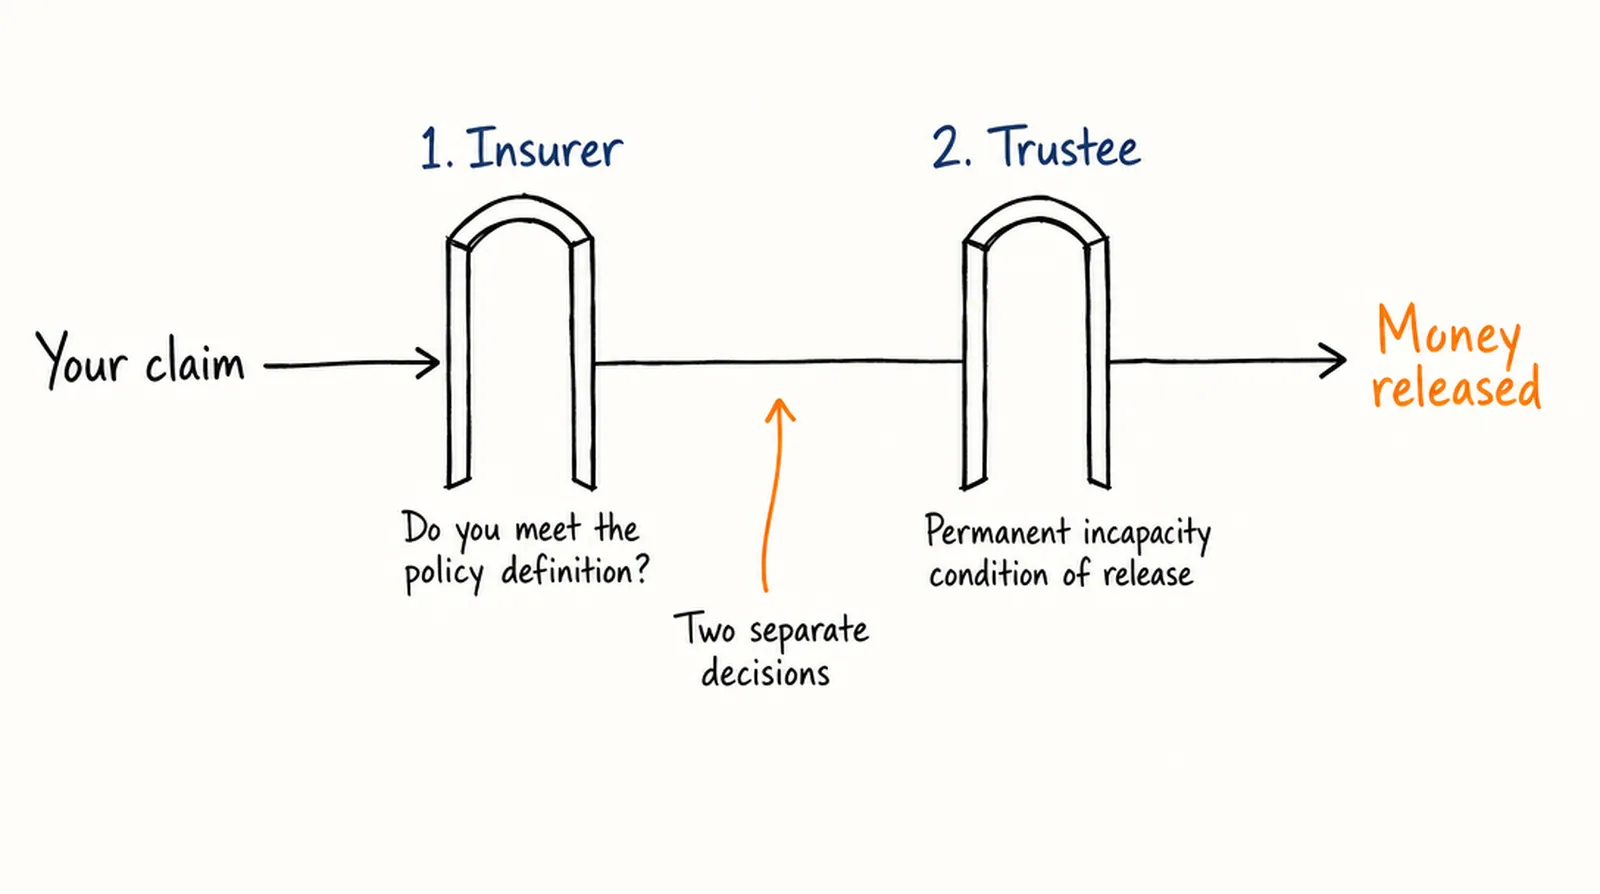
That second test is established by law, not the policy itself. Under s 10(1) of the Superannuation Industry (Supervision) Act 1993 (Cth) and reg 1.03C, a trustee must be reasonably satisfied that your ill health, whether physical or mental, makes it unlikely you will engage in gainful employment for which you are reasonably qualified by education, training or experience.
The test is whether suitable work is unlikely, not whether it is impossible, and that’s often the whole argument. A standalone policy is simpler in that there’s no second stage, and the insurer will make the final decision.
Tax: the two are treated differently
A TPD benefit paid from inside super is a superannuation lump sum and is taxed as one. A policy you own personally is not a superannuation benefit, so the super rules simply don’t apply.
For a benefit from your super fund, the ATO splits it into a tax-free component and a taxable component. Once you reach preservation age (60 for anyone born after 30 June 1964), withdrawals from both components are paid completely tax-free. Below preservation age, a tax offset caps the tax on the taxable element at 20%, plus the 2% Medicare levy, so 22% at most.
This tax treatment is more favourable if the fund treats the payment as a disability superannuation benefit. This requires two qualified medical practitioners to certify that you are unlikely ever to work again in a job you are reasonably qualified for (s 995-1(1)). Part of the taxable component then becomes tax-free to account for the working years you have lost (s 307-145(3)).
Outside super, compensation for a wrong, injury or illness you suffer personally is generally disregarded as a capital gain (s 118-37(1)). The ATO applies this provision to payments of this kind in Taxation Determination TD 2007/4. Tax treatment still depends on who owns the policy and how the premiums were treated, so confirm your position with the ATO or an accountant.
Premiums, health questions and 'limited cover'
Inside super, premiums come out of your balance, reducing your retirement savings. Outside super, you pay them yourself.
Default cover usually comes with no medical checks, useful if you have a health condition or a high-risk job. Where an insurer does not ask about your history, MoneySmart warns the policy may carry more exclusions or narrower definitions. Where you did apply, your answers are judged by whether you took reasonable care not to make a misrepresentation.
The most important exclusion is limited cover. Australian Retirement Trust's Super Savings Insurance Guide (issue date 1 July 2026) defines it as covering only a sickness that first manifests, or an injury that first occurs, on or after the date your cover started, and that is not a result of an earlier condition.
Limited cover is the pre-existing condition exclusion. It is a restriction, not a benefit, and a common reason a claim on automatic cover fails. Check your insurance guide for whether it applies, for how long, and for any waiting period. Our guide on claiming TPD with a pre-existing condition explains how limited cover works.
How much cover, and how long it lasts
Default cover is age-based and tapers steeply, usually peaking in your late twenties or thirties and falling every year after. Therefore, by age 60 it is often only tens of thousands of dollars.
In truth, however, these figures vary dramatically. Here are two real examples. AustralianSuper's Insurance in your super guide, effective 30 May 2026, gives default TPD cover of $5,000 at age 60, down from $61,000 in a member's late twenties. On the other hand, Cbus's Insurance guide (Industry Super), 1 July 2026, gives $48,000 at 60 in its default Manual category. The only reliable number is the one on your own statement.
Cover can also stop without you doing anything:
- Inactive accounts. By law, funds cancel insurance on accounts with no contributions for at least 16 months. Your fund must contact you first, and you can keep it by informing them or by adding a small amount of money.
- Age limits. TPD cover commonly ends at 65. This is for both inside super and outside super.
- Under 25 or a low balance. Cover doesn’t start automatically for a new member under 25, or where the balance has not reached $6,000, unless it's specifically requested. One exception: Moneysmart notes that cover can still start automatically if you work in a dangerous job, which is why many young construction, mining and transport workers hold it automatically.
How to Find Out Which Cover You Have
You need three facts: whether you hold TPD cover, how much, and which definition applies. The first two are on your statement, the third in the insurance guide.
- Open your latest annual super statement and find the section headed 'Insurance'. It usually shows the cover type, the amount, the premiums, and when cover ends.
- Download your fund's insurance guide or product disclosure statement, which carries the definition, the exclusions, whether limited cover applies, and any waiting period.
- Ask the fund in writing if the guide is unclear: do I hold TPD cover, what is the sum insured, and which definition applies to me.
- Check for other super accounts through the ATO online services via myGov, which shows how many accounts you have and whether they provide insurance. See also finding lost super and TPD insurance.
- Check your own paperwork. A premium notice addressed to you, or a direct debit to an insurer, points to a stand-alone policy.
Your Rights, Obligations and the Real Deadlines
You have the right to have your TPD claim assessed according to the terms of your policy and to understand exactly what your cover provides. You also have certain obligations, such as providing medical evidence and answering questions honestly.
What are your rights when making a TPD claim?
You are entitled to:
- receive the documents that explain your cover;
- have your claim assessed according to the terms of the policy;
- receive a decision based on the policy terms, rather than unrelated grounds; and
- make a free complaint to AFCA if you disagree with the fund's decision.
AFCA's rules also state that there’s no monetary limit on superannuation complaints.
What are your obligations when making a TPD claim?
You generally need to:
- provide medical evidence that supports your claim and meets the policy definition;
- attend an independent medical examination if required; and
- answer questions honestly when applying for cover.
Is there a deadline for making a TPD claim?
There is no statutory deadline for lodging a TPD claim with your super fund. This means you can potentially make a claim years after you stopped working, and funds do regularly accept claims made long after the person's employment ended.
However, different time limits apply if you later complain to AFCA about the fund's decision.
How long do you have to complain to AFCA about a TPD decision?
For a TPD claim through super, AFCA's Rule B.4.1.1 applies:
- If you permanently stopped working because of the condition you're claiming for, you generally need to have made the claim within two years of stopping work and lodged your AFCA complaint within four years of the fund's decision.
- Otherwise, you generally have six years from the fund's decision to lodge the AFCA complaint.
These time limits cannot be extended by AFCA, and asking the fund for an internal review does not restart the clock. The relevant period runs from the original decision.
What if the TPD policy is outside super?
Different rules apply when you hold TPD cover outside super. Under AFCA Rule B.4.3.1, the complaint deadline is generally the earlier of:
- six years from when you became aware of the loss; or
- two years from the insurer's internal dispute resolution response.
Common Questions
I am a tradie. Why would my super TPD claim be rejected for a back injury I sustained?
As 'any occupation' asks about any suitable work, not your trade, this may have led to the claim being rejected. An insurer may argue that you could do lighter or office-based work that you are reasonably qualified for. But that conclusion can be challenged: the test is whether suitable work is unlikely, and evidence of your pain, medication and failed attempts to return to work can help show this. Ask the insurer to explain its reasons in writing.
Can I claim on more than one super fund?
Possibly, but it depends on the policies. Moneysmart's position is that where you hold more than one super account, you may be paying premiums on more than one policy, and may not be able to claim the full benefit from more than one. Check each policy for offset clauses, and see our guide to TPD insurance when consolidating super.
Should I buy a stand-alone policy as well as my super cover?
That is a financial advice question rather than a legal one. Own occupation cover is a lower bar to meet than the any occupation cover inside super, which is why it comes up for people in specialised or physically demanding work. Whether it suits you is a conversation for a licensed financial adviser.
When to Seek Legal Advice
The success of a claim turns on how one form of words applies to your own history. The insurer knows this. What legal advice can do is identify the relevant definition, test the evidence against it, and challenge gaps or weaknesses in the insurer’s reasoning.
Consider getting advice if:
- Your fund says you hold no cover, or less cover than you expected, and you cannot work out why.
- Your claim has been declined and the reasons do not match your medical evidence. Our guide to the common reasons for TPD claim denials covers what usually goes wrong.
- You are told that limited cover or a pre-existing condition exclusion applies to you.
- You stopped work some time ago and have been told you are too late to claim.
- You are close to one of the AFCA time limits outlined above.
Key Takeaways
- Default cover in super is the common case. If you never applied and never paid a premium yourself, that is almost certainly what you hold.
- The definition matters more than the amount. Own occupation cover has not been available inside super for cover starting on or after 1 July 2014.
- Acceptance is not payment. The insurer decides the policy claim; then the trustee must be satisfied of the permanent incapacity condition of release, and that test is 'unlikely', not 'impossible'.
- The tax paid depends on where the cover sits. A super benefit can be taxed below age 60; a personally owned policy generally is not.
- There is no deadline to lodge with your fund, but AFCA's time limits are strict and cannot be extended.
Get Help Now
If you are not sure what cover you hold, or your TPD claim has been declined, Smith's Lawyers offers a no-obligation review of your situation with no upfront cost. A qualified member of the team will assess your rights, explain your options and let you know the best course of action.
Fixed-fee arrangements are available in some situations. Otherwise, our fees reflect only the work done, and are payable only if the claim succeeds.
Contact Smith's Lawyers today:
- Call 1800 960 482 for a free, no-obligation consultation about your situation
- No upfront costs: We operate on a No Win, No Fee, No Catch® basis; you only pay if we secure compensation for you
- Or request a call back: Use the form below to have our experienced team get in touch at a time that’s convenient for you.