You may be able to make a TPD claim through your super fund for a mental health condition such as PTSD, depression or anxiety.
What decides the claim is not your diagnosis. It’s whether your condition makes it unlikely you will work again in a job you are reasonably suited to.
The factors that decide this are usually:
- Education
- Training
- Experience
This article will clearly detail the necessary steps to make a TPD claim if what is stopping you from returning to work is an issue such as PTSD, depression or anxiety.
Is a Mental Health Condition Covered by TPD Insurance?
Generally, yes. Nothing in the superannuation rules treats a psychiatric condition as being different from a physical claim.
Permanent incapacity, the necessary condition that allows you to be paid from your super, is defined by reference to the member's ill-health ‘whether physical or mental’ (Superannuation Industry (Supervision) Act 1993 (Cth), s 10(1), and Superannuation Industry (Supervision) Regulations 1994 (Cth), reg 1.03C). The AFCA rule governing TPD complaints also uses the same wording.
Insurers who subscribe to the Life Insurance Code of Practice also commit not to introduce new products with a blanket mental health exclusion, consistent with the Disability Discrimination Act 1992 (Cth).
Two things can still affect this:
- An exclusion can apply to you after underwriting if it’s based on reasonable actuarial or statistical data. This means an insurer may exclude a condition based on your individual circumstances and the available evidence.
- Your cover may start as limited cover, meaning it only covers conditions that arise after your cover begins. This means you may not be covered for a condition you already had when your cover started.
Checking whether you hold cover
Cover through super is common, but it is not automatic, so this is the first thing that should be checked. This matters most if you have had gaps in your work history.
Your super fund generally cannot provide insurance if:
- Your account has been inactive for 16 continuous months.
- Your balance is under $6,000 and has never reached $6,000 since 1 November 2019.
- You are under 25, unless you have chosen in writing to keep your cover.
You may also have cover through an old super account you have forgotten about. Our guide ‘How To Find Lost or Forgotten Superannuation in Australia’ can help you if this is the case.
What the Test Actually Asks
Inside the majority of super funds, there’s an ‘any occupation’ test that assesses whether you are unlikely to work again in any job you are reasonably suited to, rather than whether you can return to the job you had (‘own occupation’). For example, an airline pilot with PTSD still may be able to work an office job.
Under Reg 1.03C, the question is whether your illness or injury makes it unlikely that you will be able to participate in gainful employment, meaning paid work you are reasonably qualified to do based on your education, training or experience. Limited or unsustainable work does not automatically rule you out.
The same standard applies to TPD cover through super because of reg 4.07D. Since 1 July 2014, super funds can only provide insurance where the insured event matches a condition for releasing your super. For TPD, this means permanent incapacity.
If you joined your fund before 1 July 2014, your cover may be protected under the old rules. If you have older cover, it is worth checking which definition applies to you.
Some policies contain a stricter alternative test based on activities of daily living, which asks whether you can perform basic self-care tasks without help. Your insurance guide will explain which applies to you. You may also wish to read our guides on own occupation and any occupation cover and activities of daily living that clearly set out the difference.
You don’t need to have been in hospital, and you don’t need to have tried everything.
The definition asks whether it is unlikely you will engage in suitable paid work. It does not ask whether you have been admitted to a hospital or any other institution or whether you’ve tried every intervention possible. However, many policies do consider whether your condition is likely to improve with reasonable further treatment, which is why a consistent treatment record matters.
How Much Is Paid, and Why Severity Doesn’t Change the Amount
The amount you receive is the TPD sum insured recorded under your fund's policy. It does not change based on how severe your condition is or what your diagnosis is. The key question is whether you meet the policy's TPD definition. This is generally a yes or no test.
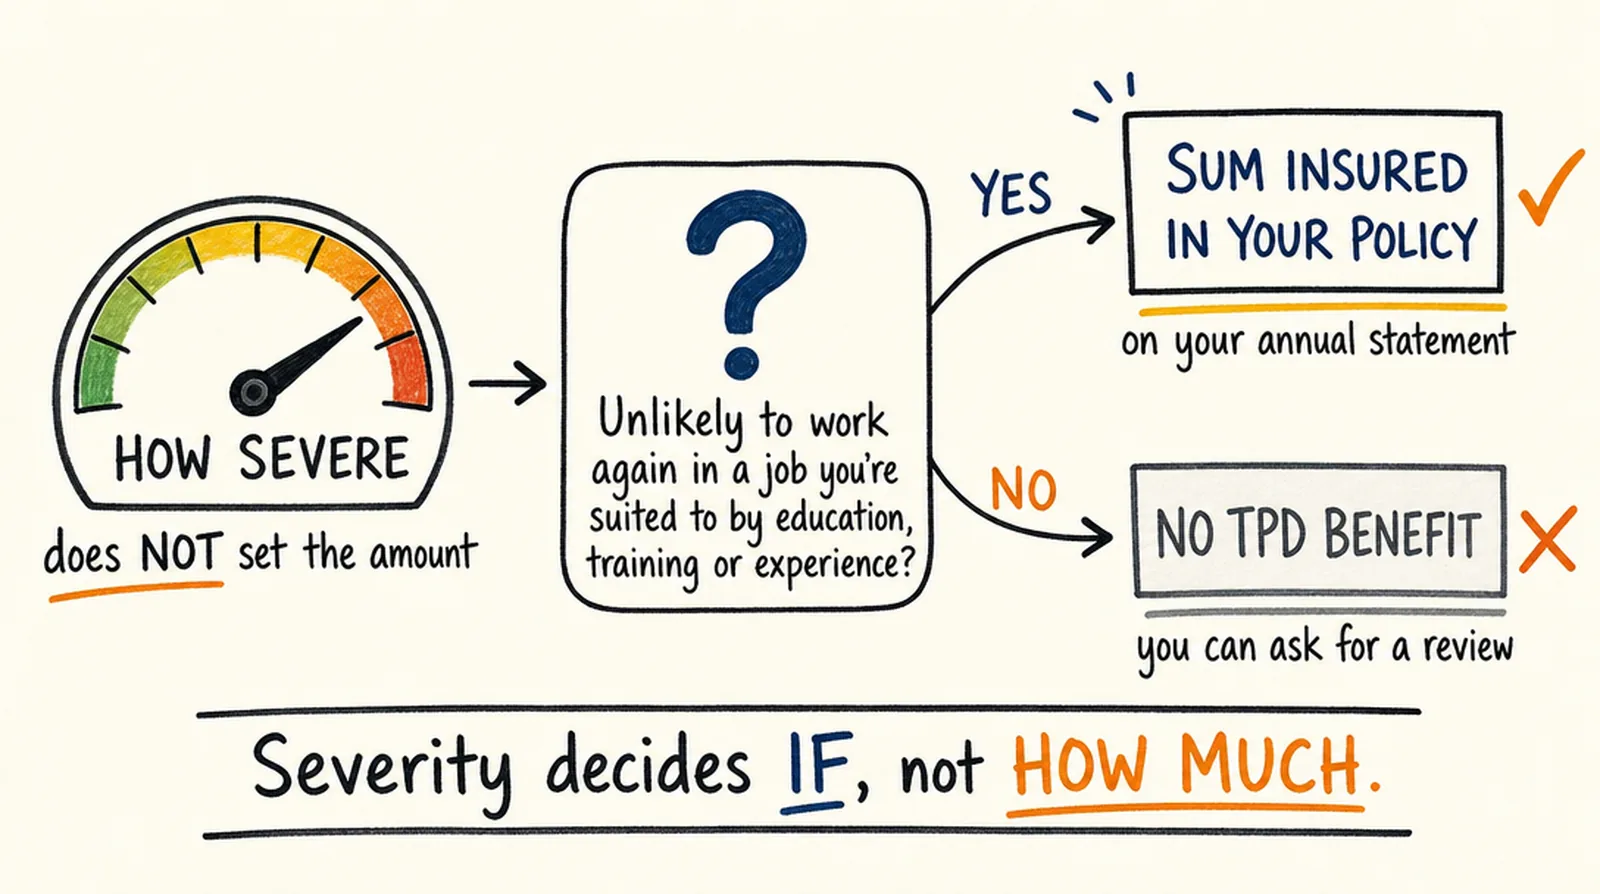
Your annual statement or insurance guide will show your TPD cover amount. Waiting periods vary between funds and policies, so there is no standard waiting period. If your insurer follows the Life Insurance Code of Practice, as mentioned above, it must tell you your cover amount and any waiting period within 10 business days of receiving your claim.
The Evidence That Does the Work
Medical evidence here does one job, which is to connect a diagnosis to a loss of capacity for suitable work over time. Each document helps establish the entire story of your condition:
- Treating psychiatrist's report. The diagnosis, the treatment given, the response to it, and a considered view on prognosis and capacity for work.
- Treating psychologist's report. What the condition looks like session to session, and functional detail one consultation cannot capture.
- GP records. When symptoms started, how continuous treatment has been, what medication was tried, when referrals were made.
- Hospital or clinic records, if any. These will detail the acute episodes, but won’t be considered a gap in your records if they are missing.
- Employment records. Your actual duties and hours, the date you last worked and reasons for this, as well as any adjustments or return-to-work attempts. An attempt that didn’t work out is evidence, not something to hide.
- Your education, training and work history. This sets the field of suitable work you are measured against.
- A plain account of an ordinary day. Sleep, concentration, leaving the house, managing appointments.
Many mental health conditions fluctuate. The question is your capacity to hold suitable work, not your capacity on a better day, so evidence recording both your worse periods and your usual baseline gives an assessor more to work with. Our guide to medical evidence in mental health TPD claims addresses this further.
How to Make the Claim
- Get your policy documents. Ask your fund for the insurance guide that applied when you stopped work, plus your annual statements. You want the sum insured, the definition, and any waiting period.
- Fix in the date you last worked, and the reasons why. This is doubly important, as it forms part of the policy’s conditions and the time limits set out by the AFCA.
- Tell your practitioners what the claim needs. Give your psychiatrist, psychologist and GP a copy of the definition, so their reports address the wording it is assessed against.
- Lodge with the fund. Most funds take the claim and pass it to the insurer. Keep a copy of everything and the date you sent it.
- Follow up in writing. Where the insurer subscribes to the Life Insurance Code of Practice, it must update you at least every 20 business days, and answer a request for information about your claim within 10 business days.
The general sequence is in our TPD claims process guide.
Your Rights While the Claim Is Being Assessed
The available protections during a claim come mostly from the Life Insurance Code of Practice. It does not bind superannuation fund trustees unless a trustee has adopted it. A full list of those who subscribe is published on CALI’s website.
Decision timeframes. For a lump sum benefit such as TPD, the insurer will decide within six months of the claim received date or the end of any waiting period, whichever is later, and will tell you the decision in writing within 15 business days of holding everything it reasonably needs. If circumstances beyond its control mean it cannot meet the six months, it must say so in writing before the six months expires and update you at least every 20 business days.
The claim received date is set by the insurer when it receives enough information to start assessing your claim. Time spent with the fund before this date does not count towards the six-month period. This can make the process feel longer.
Independent medical examinations. You can ask for a list of doctors to choose from, and for at least one doctor of each gender on that list where practical. The insurer pays for the appointment, the reports, reasonable travel and out-of-pocket costs that are agreed in advance.
Interviews. The insurer will arrange an interviewer it is satisfied has appropriate training and experience to discuss a claim involving a mental health condition where relevant. Interviews take no more than 90 minutes unless you agree in writing. Plus, you get a five-minute break at least every 30 minutes and can ask for more or to end early, and you can ask to be interviewed away from your home unless interviewing you there is essential.
Surveillance. This has to be approved internally, and only after the insurer has tried to resolve any inconsistencies without it. If an investigator is appointed, the insurer must require them to stop if evidence is received from a doctor, psychologist or other appropriate person that the surveillance is harming your health, including your mental health. That evidence will not be used against you in evaluating your claim.
Support. If you need extra support, tell the insurer and it will work with you to find a suitable option. You can have someone with you to provide support, including a lawyer, interpreter, family member, carer or friend.
Common Questions
Can I claim if my PTSD did not come from work?
Yes. TPD cover through super is not limited to work-related conditions, and reg 1.03C says nothing about how the ill-health arose. Trauma from a road crash, an assault or an event in your private life can support a claim on the same terms. What has to be established is the effect on your capacity for work.
My condition is work-related. Can I claim twice?
You may have two claims running at once. Every state and territory runs a workers' compensation scheme that can cover work-related psychological injury, and in Queensland that scheme sits under the Workers' Compensation and Rehabilitation Act 2003 (Qld). Our guide on claiming TPD and workers' compensation at the same time explains how they fit together.
Does the insurer accepting my claim mean the money is released?
No, those are two separate decisions. The insurer decides whether the policy definition is met. The trustee must then be reasonably satisfied that you meet the permanent incapacity condition of release before your benefit can be paid out of your super (SIS Regulations, Schedule 1 item 103 and reg 1.03C). Although the decisions concern the same issue, they are made separately, which can create a gap between claim acceptance and payment.
What if my claim is declined?
You can ask for the decision to be reviewed. The trustee should give you a final written response within 45 calendar days of receiving your complaint (ASIC Regulatory Guide 271, Table 2). You can then take it to the AFCA, which is free for consumers and has no monetary limit on superannuation complaints.
AFCA's own time limits are strict. If you permanently stopped work because of the condition you claimed for, the claim must have been made to the fund or insurer within two years of you permanently stopping work. The AFCA complaint must be lodged within four years of the decision on that claim. If you stopped work for another reason, the limit is six years from the decision. Asking for an internal review does not restart the clock, because AFCA measures from the original decision, and it will not extend these limits.
When to Seek Legal Advice
Many assume that legal advice is sought to assist with the paperwork. This couldn’t be further from the truth. In fact, the main reason to seek legal advice is to ensure that the wording applied to your history is correctly used.
Also, consider advice if:
- Your fund says you hold no cover, or less than you expected, and you cannot see why.
- You are asked to account for treatment gaps, periods of work, or a delay before claiming.
- Your claim has been declined, or has sat without a decision past the six-month Life Insurance Code of Practice timeframe.
- You are close to one of the AFCA time limits as outlined above.
Key Takeaways
- A mental health condition is claimed through TPD in the same way as a physical condition. The superannuation definition and the AFCA rule both allow for ‘physical or mental’ conditions.
- The test is most often about suitable work, not your old job, measured against your own education, training and experience (‘any occupation’ definition as opposed to ‘own occupation’).
- Severity decides whether the definition is met, not how much is paid. The amount is the sum insured under your fund's policy.
- The Life Insurance Code of Practice gives you concrete rights if your insurer subscribes to it, including a six-month decision timeframe, a choice of doctors for an independent examination, and limits on interviews and surveillance.
- Acceptance is not the same as payment. The trustee must be separately satisfied of the permanent incapacity condition of release before the money leaves your super.
Get Help Now
If you are dealing with a TPD claim for a mental health condition and want it looked at properly, Smith's Lawyers offers a no-obligation review of your situation with no upfront cost. A member of the team will assess your rights, explain your options and let you know the best course of action.
Fixed-fee arrangements are available in some situations. Otherwise, our fees reflect only the work done and are payable only if the claim succeeds.
Contact Smith's Lawyers today:
- Call 1800 960 482 for a free, no-obligation consultation about your situation
- No upfront costs: We operate on a No Win, No Fee, No Catch® basis; you only pay if we secure compensation for you
- Or request a call back: Use the form below to have our experienced team get in touch at a time that’s convenient for you.