You can ask your super fund or insurer to review a declined Total and Permanent Disability (TPD) claim at any time.
There is no law which sets a deadline for making that request, so a letter of decline from months ago is still open to challenge. The deadlines that can genuinely end a claim are to do with the Australian Financial Complaints Authority, and superannuation TPD decisions are measured in years, not weeks.
There is no 28-day deadline
There is no Australian law which puts a 28 day limit, or any other, on challenging a declined TPD claim.
You can request a review at any time, including while a claim is still being assessed. The 28-day figure that circulates online is the objection period for superannuation death benefit distributions, which is a completely different process.
The 45 days are for the fund, not you. Under ASIC's Regulatory Guide 271, a superannuation trustee must give you a written response no later than 45 calendar days after receiving your complaint.
Where an insurer handles a complaint outside super, the maximum is 30 calendar days. These time limits only begin when you complain, so nothing runs against you while you’re gathering evidence.
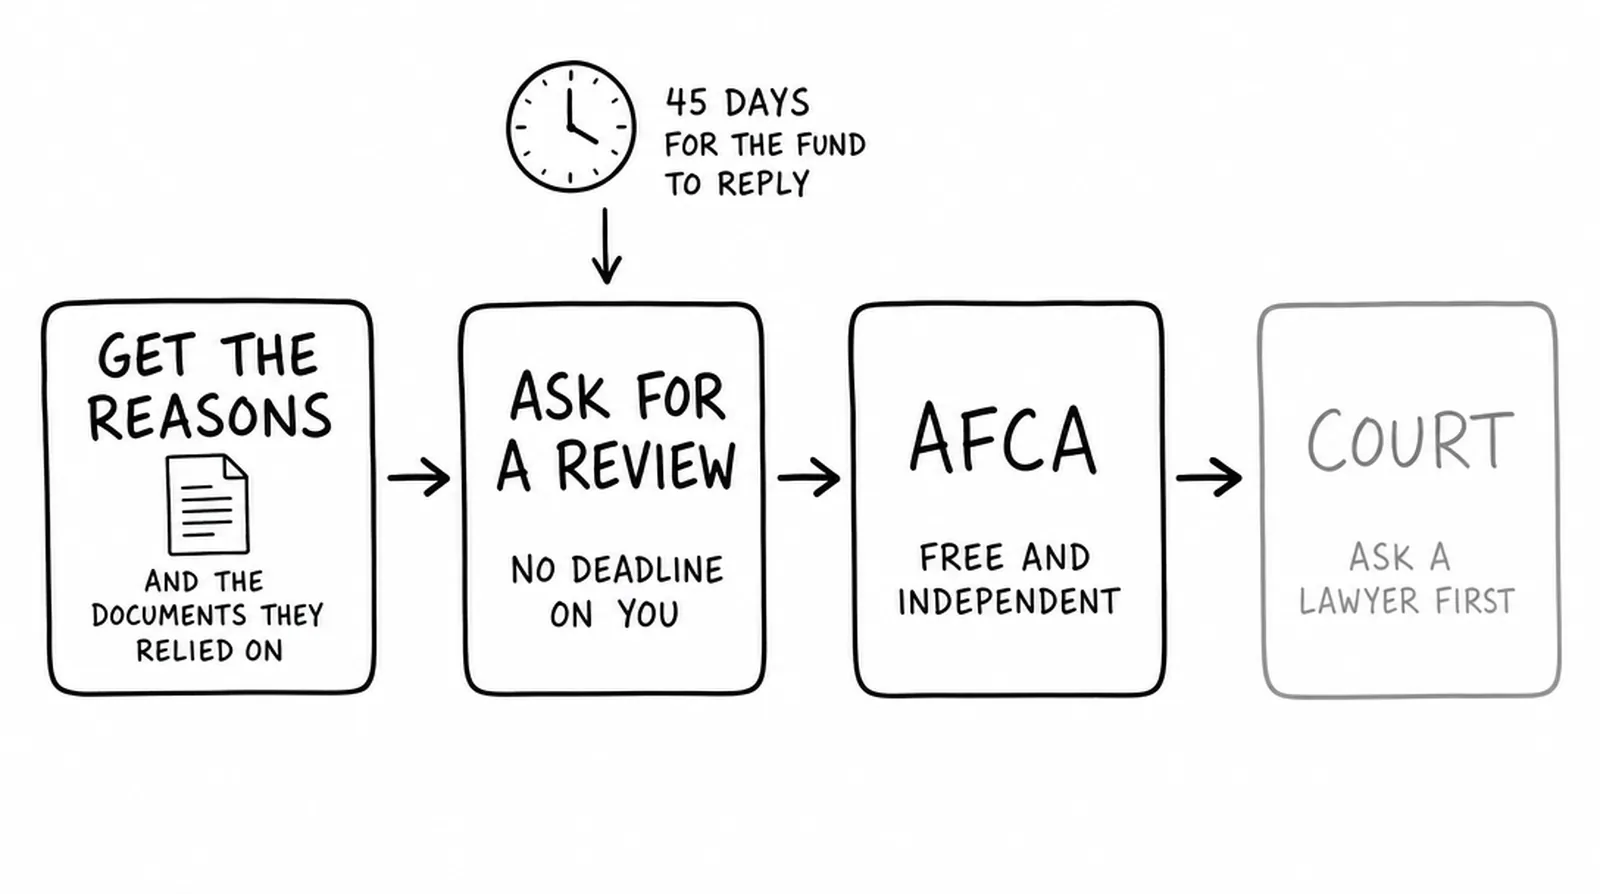
Step one: get the reasons and the documents
Before you do anything, find out exactly what was decided and what the decision was based on. A letter that gives you a conclusion without the reasons for your rejection isn’t enough, and the real reason for a decline is usually narrower than the letter first makes it seem.
First, check that a decision has actually been made. If you have a procedural fairness letter, it is not actually a rejection.
The Life Insurance Code of Practice defines this as a letter setting out the insurer's preliminary view to give you a chance to respond before it decides. Clause 5.52 of the Code requires the insurer to tell you how long you have and to allow a reasonable period for your response.
Answering a procedural fairness letter properly is the cheapest opportunity you get because it comes before the decision rather than after.
The Life Insurance Code of Practice binds the life insurers that subscribe to it, and the March 2025 version has been in effect since 1 March 2025. The subscriber list is on the Council of Australian Life Insurers website.
Clause 5.58 states that in the event your insurer declines a claim, it must tell you in writing:
- Its reasons and a summary of the information it relied on.
- If a pre-existing condition is the reason, the medical connection between that condition and your claim.
- That you can ask for copies of the documents it relied on, which it will send within 10 business days.
- That you can ask it to review the decision or give it more information.
- How its complaints process works.
If the insurer does withhold something, clause 3.14 requires it to list what it has withheld, explain why it has done so and tell you how to make a complaint.
Separately, Australian Privacy Principle 12 gives you a right to the personal information an organisation holds about you, which covers the reports, file notes and assessments on your claim file.
Step two: ask the trustee or the insurer to review the decision
This is where most declined claims are either resolved or properly set up for the AFCA, and there is no entry deadline for it.
If your cover is held through superannuation, you can make a complaint to the insurer or the trustee. This is valuable because it means you can add evidence that the original assessor never saw.
The response must tell you the outcome, your right to go to the AFCA and the AFCA's contact details. If a complaint is rejected, RG 271.54 requires the trustee or insurer to address the issues you raised, set out the findings on material questions of fact with the information supporting them and give you enough detail to decide whether to escalate. Both are enforceable.
Code clause 5.57 adds a reassessment route. You can ask the insurer to reopen or reassess a closed or declined claim, and if it agrees, the Code's timeframes start again from the new claim received date.
You should put in reports from your treating doctors addressing what you can and cannot do at work, rather than just your diagnosis, as well as evidence of what your job involved. You should also include any push back on an unexplained delay past the 45 days, and on a decision which was made based solely on an insurer-appointed doctor's report.
If the problem is delay rather than a decision, see our guide on what to do when your insurer is delaying your TPD claim.
Step three: take it to the AFCA
The Australian Financial Complaints Authority is a free, independent body that can review a trustee's or insurer's decision on a TPD claim. It is not a court, and its decisions bind the financial firm if you accept them. This is where time limits finally matter, because the AFCA's are strict.
The two-year point is very important. There is no law which sets a deadline for lodging a TPD claim with your super fund, but if you permanently stopped work because of the condition you are claiming for, the AFCA can only consider a complaint if the claim was made within two years of you stopping work.
The AFCA will not extend these limits. Rule B.4.4.1 states this clearly: “AFCA will not extend any of the time limits set out in rules B.4.1.1 to B.4.1.4.” A special-circumstances extension exists elsewhere in the rules, but not for this one.
There are two other important things about this pathway:
- There is no monetary limit on a superannuation complaint. Rule D.4's caps apply to other complaints, and Rule D.1.3 confirms there is no limit here. The roughly $1 million ceiling that is sometimes quoted is the non-superannuation consumer cap.
- The test is about fairness. The AFCA must affirm the decision if satisfied it was fair and reasonable in all the circumstances (Rule D.1.2, reflecting s 1055 of the Corporations Act 2001 (Cth)). If it doesn’t, the AFCA can vary it, substitute its own decision or remit it to the trustee with directions (Rule D.1.1).
Going to the AFCA before making a complaint with the fund does not shut you out. In fact, the AFCA will normally refer the complaint back to the firm and set a time to respond (Rule A.5.2).
The trap: an internal review does not give you more AFCA time
Going through an internal review might make it seem like the clock should be paused, but it isn’t, and this is the point that’s most likely to cost someone their rights.
The four or six year time limit runs from the first decision you were given, regardless of how long the review takes or its conclusion.
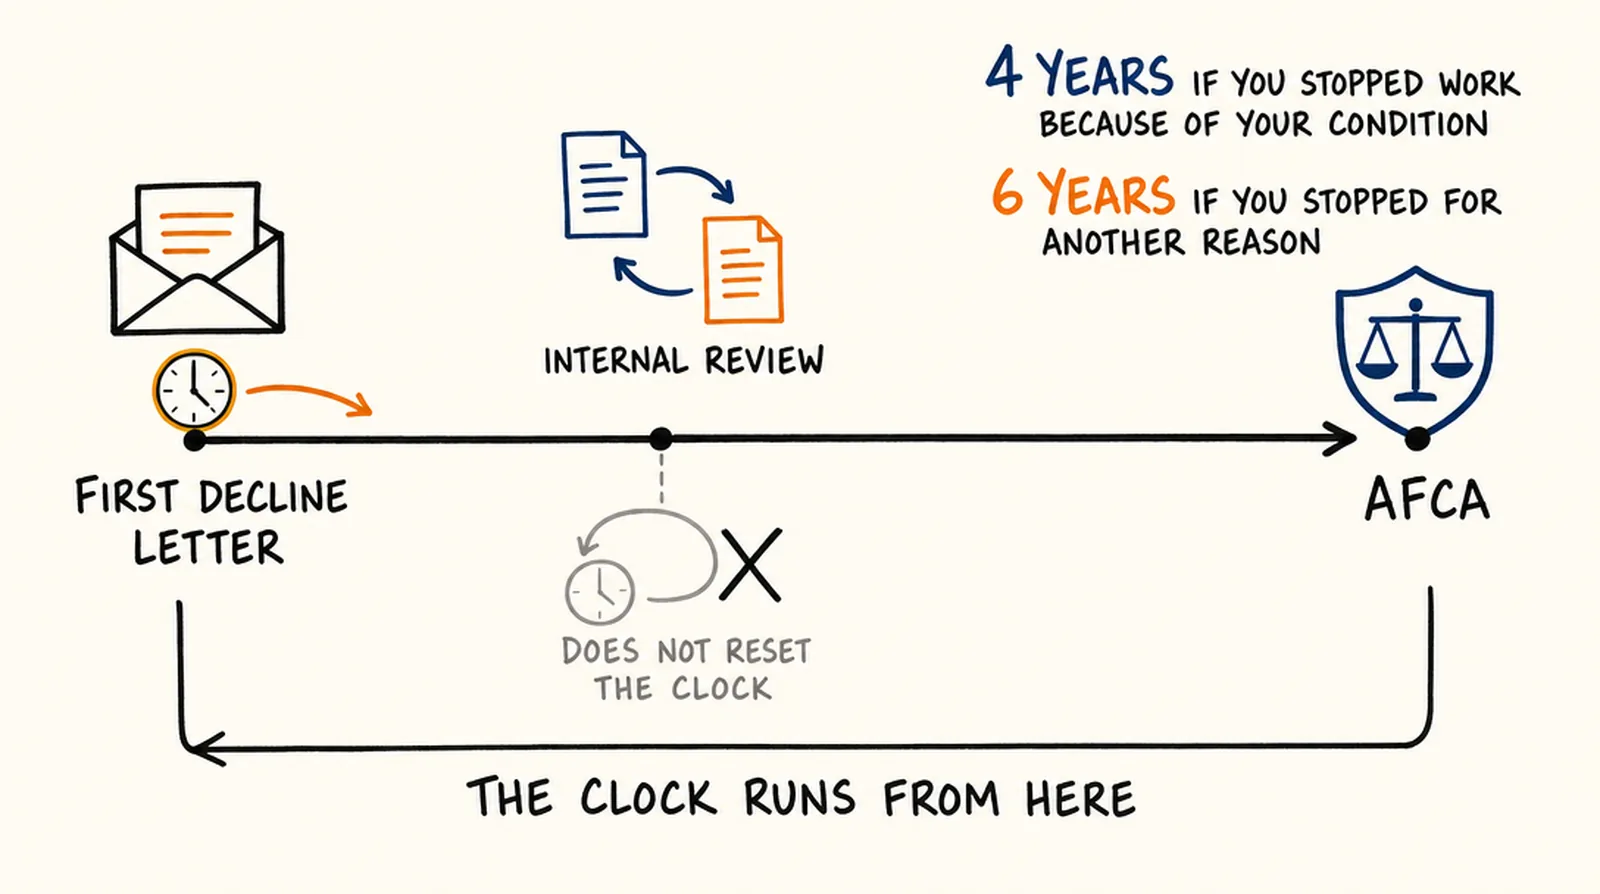
AFCA Rule B.4.1.2 says that where a complaint to the decision maker results in the original decision being confirmed, or another decision being substituted for it, that later decision is taken to be the original decision and is taken to have been made at the time the original decision was made.
So, you should count the date from your original decline letter. If that date is getting close to four years, it’s a good idea to get advice now rather than waiting for the internal process to finish.
If AFCA does not resolve it, is court an option?
Court is available in principle, and it is a different proposition that’s slower, more formal and normally requires legal representation.
The Insurance Contracts Act 1984 (Cth) does apply to group life cover held through superannuation, but it has no limitation period, despite being widely cited as if it does.
Time limits for court proceedings come from the relevant State or Territory Limitation Act, which means that the one which applies hinges on how your cover is held and who you would be suing.
It’s a good idea to engage a lawyer to work through your own dates.
Why TPD claims get declined, and what answers each reason
Most rejections are because of a few recurring reasons, each answered by a different kind of evidence. Our guide to the common reasons for TPD claim denials covers them in more detail.
Working out which you are facing is the most useful thing you can do because a well-evidenced answer to the wrong question won’t actually change anything.
There’s one important point worth keeping in mind if you are facing a pre-existing condition argument: under the Insurance Contracts Act 1984 (Cth), an insurer cannot rely on a pre-existing condition exclusion where the person insured was not aware, and a reasonable person in the circumstances could not be expected to have been aware, of the sickness or disability when the cover was entered into. The pre-existing conditions guide explains how this works.
If my claim is approved on review, is the payout tax free?
Not automatically, and this is worth working out properly before you plan around a specific figure. A TPD benefit paid out of superannuation is considered a superannuation lump sum. Its tax-free component is not taxed, and if you are under your preservation age (now 60), the tax on the taxable component is capped at 20% by an offset under the Income Tax Assessment Act 1997 (Cth), plus the 2% Medicare levy, so 22% at most.
Because TPD benefits are usually a disability superannuation benefit, part of what would otherwise be taxable is shifted into the tax-free component to reflect the working years you have lost.
This reduces the amount you’re taxed, often substantially for younger claimants, but it does not make the payment tax free. Two legally qualified medical practitioners will need to certify that it’s unlikely you will ever be gainfully employed in a capacity you are reasonably qualified for, so check that your payment summary shows the benefit was treated that way.
Cover outside super, and unfunded public sector schemes, is also taxed differently.
Does the insurer accepting my claim mean I get paid?
Not on its own, if your cover is held through superannuation. Before the money is paid out, a trustee must also be reasonably satisfied that your ill health makes it unlikely you will be able to engage in gainful employment for which you are reasonably qualified by education, training or experience.
That is the permanent incapacity condition of release, and it is a separate question that’s decided by a different party.
When to get legal advice
Making an internal complaint and going to the AFCA are both open to you directly. The AFCA is free, so many people handle a straightforward review themselves, but a lawyer knows exactly which limb of the policy definition your evidence has to meet, and what has persuaded the AFCA on comparable facts before.
It’s always a good idea to seek legal advice in cases such as these, especially if:
- It is approaching four years since your original decline letter and you permanently stopped work because of your condition, or it’s approaching two years since you stopped work and have yet to lodge a claim.
- You hold cover with more than one fund or have rolled money between funds, and it is unclear which cover was active when you stopped work.
- The insurer says your condition is pre-existing, or that you were on limited cover, and you disagree about when it arose.
- You also have a workers' compensation or income protection claim, which interact with this one on different tests. See this handy article on WorkCover, TPD and income protection claims for more information.
- You are told a deadline has passed and nobody names the rule, or the fund has gone past its 45 days without explaining why. See how long a TPD claim takes here.
Early advice is most important for the definition question because evidence gathered against the wrong test does not become useful later, and by then a stage has been used up.
Get Help Now
If your TPD claim has been declined and you are not sure what stage you are at or how much time you have left, we can read your letter and your dates and tell you where you stand. Smith's Lawyers acts on superannuation insurance claim (TPD) matters across Australia, including internal reviews and AFCA complaints.
Call 1800 960 482 or enquire online using the form below.
Our TPD experts work on a No Win, No Fee, No Catch® basis, so there are no upfront legal costs.
You can also use the form below to request a free claim review.