You may be eligible to claim TPD (Total and Permanent Disability) insurance if you have TPD cover, which is commonly held through your super fund.
Whether your claim succeeds depends on your policy's definition of total and permanent disability, whether your illness or injury permanently prevents you from working, and whether you have met the required waiting period.
Understanding TPD cover
TPD insurance pays a lump sum if an illness or injury leaves you permanently unable to work. According to ASIC's MoneySmart, it is one of the most common types of cover held inside superannuation.
Where your cover usually sits
Most people hold TPD cover automatically through their super fund, bundled in when the account was opened. You do not have to buy it separately, and many claimants only discover the cover exists after they stop working.
Because it is attached to your super, the cover can sit quietly in an old or forgotten account. This is why checking every fund in your name matters, especially as you can claim from multiple supers at once. Our guide on finding lost super and TPD insurance explains how to trace them.
If you are not sure whether your cover is inside or outside super, see our comparison of TPD cover in super versus a stand-alone policy.
Why the policy definition decides your claim
Eligibility is not just about being unwell. It is about whether your condition meets the specific definition of disability written into your policy.
Two people with the same injury might get different answers if their policies test disability differently. The definition is the single biggest factor in whether you qualify, so let’s cover this clearly below.
Own-Occupation vs Any-Occupation Cover
The definition in your policy sets the bar you have to clear. MoneySmart describes the two main definitions used in TPD policies, and a third that some policies fall back to.
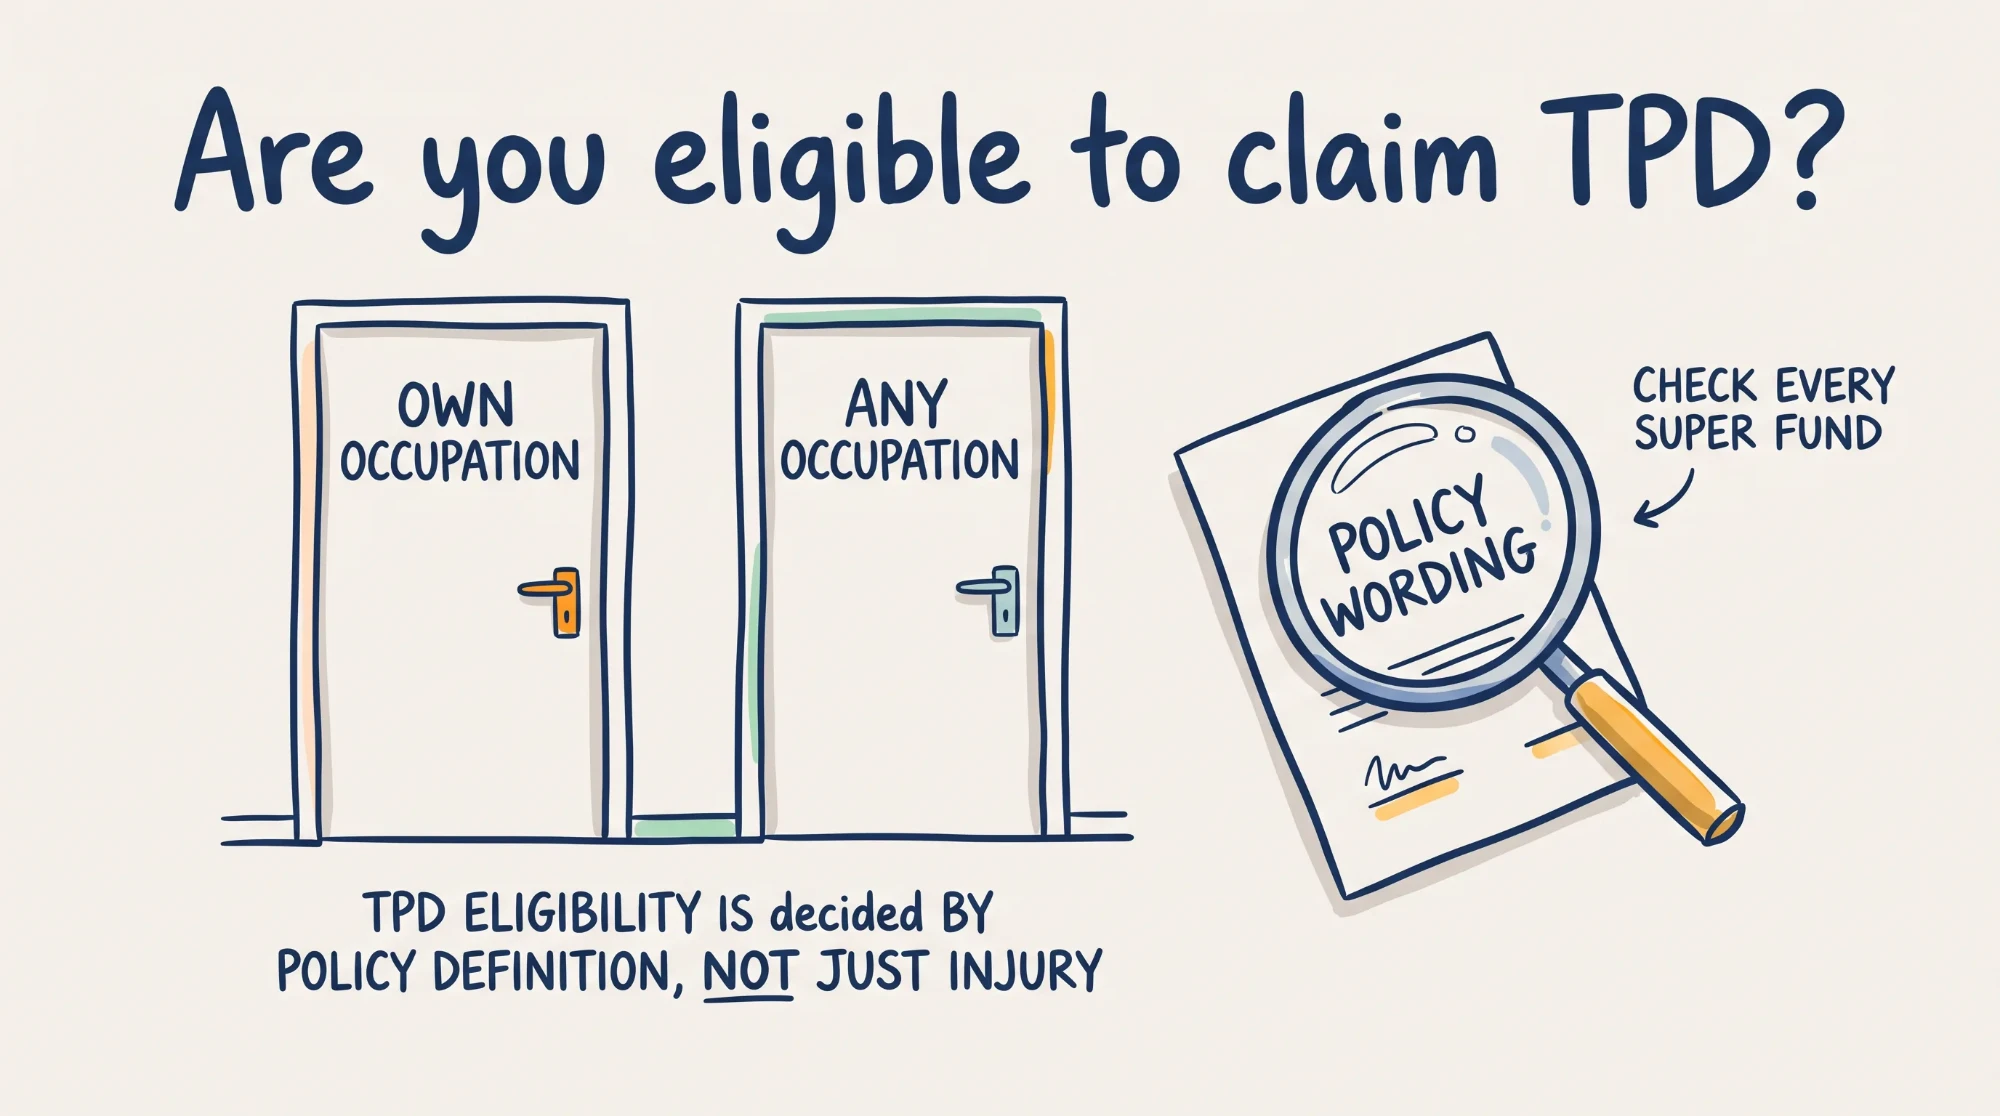
An any occupation policy requires you to show you can no longer work in any job you're reasonably qualified for through your education, training, or experience, while an own occupation policy only requires you to show you can no longer perform your usual job.
Any occupation is the more common definition in super fund TPD insurance and is generally the more difficult test to satisfy. For more detail, see our guide to own occupation versus any occupation cover.
Some policies also include an activities of daily living test, which asks whether you can perform basic self-care tasks such as bathing, dressing and mobility without help. Our guide to the activities of daily living definition explains how it works. Knowing which definition applies to you is the first step in working out if you are eligible.
What Decides Whether You Are Eligible
Three things generally have to line up for a TPD claim to be successful.
What you need to have:
- Active TPD cover at the relevant time, usually through one or more super funds.
- A serious illness or injury that is expected to be permanent.
- Medical evidence that you can no longer work under your policy's definition.
What you must be able to show:
- You have met the policy waiting period, commonly a continuous 3 or 6 months off work.
- Your incapacity fits the definition in the policy (any-occupation, own-occupation, or activities of daily living).
- The cover was in place when your condition arose. This matters more than which fund you are part of currently.
- There is also a second step. Once the insurer accepts your claim, your super fund’s trustee must separately be satisfied that you meet the permanent incapacity condition of release before the money can be paid to you. It is a different test from the policy definition.
How to Check What Cover You Have
You can confirm your TPD cover yourself before speaking to anyone. The Australian Taxation Office lets you see every super account linked to your tax file number in one place.
- Log in to myGov and open ATO online services. You will need your myGov account linked to the ATO. Have your tax file number to hand.
- Go to Super, then Fund details. This lists all current super accounts held in your name, including funds you may have forgotten or lost track of.
- Note every fund, including old ones. Cover can sit in an account you stopped contributing to years ago. Write down each fund and account number.
- Read the insurance section of each fund's latest statement. Log in to each fund or call the provider, and look for or ask for TPD or ‘death and TPD’ cover, the sum insured, and the disability definition.
- Check the definition and waiting period for each policy. These are the two details that decide eligibility, so record them for every fund that offers you cover.
If you plan to consolidate your super, check your insurance first. The ATO warns that any cover attached to an account you close is usually cancelled, so confirm your TPD cover before rolling funds together. See our guide on TPD insurance when consolidating super.
Common Scenarios and Questions
Do I have to be injured at work to claim TPD?
No. TPD cover is based on your inability to work, not on how or where the injury or illness happened. A back injury at home, a chronic illness, or a mental health condition can all support a claim if they permanently stop you working under your policy's definition. This is a key difference from workers' compensation, which does require a connection with your job.
What if I have super in a fund I forgot about?
You may still have TPD cover sitting in that account. Old and inactive super accounts often carry insurance the member has forgotten. Use the ATO super search through myGov to find every fund, then check each one for cover before you assume you have none.
Do I even have TPD cover if I’m under 25?
Possibly, but not automatically. Under the Treasury Laws Amendment (Putting Members' Interests First) Act 2019 (Cth), which took effect on 1 April 2020, super funds generally do not provide insurance by default to members under 25 or with balances under $6,000, unless the member opts in.
According to APRA's guidance on the Putting Members' Interests First reforms, an exception applies to certain dangerous occupations. We recommend checking whether you’ve opted in at some point and have forgotten, or whether you fall within the list of exceptions.
What if my account went inactive and the insurance was cancelled?
Your cover may have been switched off, but it is worth confirming the exact date. Under the Treasury Laws Amendment (Protecting Your Superannuation Package) Act 2019 (Cth), insurance on accounts inactive for 16 months is cancelled unless the member elects to keep it. If your condition arose before the cover ended, you may still be able to claim, so the timing is important.
Does it matter which fund I'm in now versus when I became unable to work?
Yes. What usually matters is the cover you held at the time your condition met the policy definition, not the fund you are in today. People sometimes assume a claim is lost because they have since changed funds. That is not necessarily the case, which is why the date your incapacity began is a critical detail.
Can I claim if I have returned to some form of work?
It depends on your policy definition and the type of work. Under an any-occupation policy, returning to a job suited to your training may affect eligibility, while limited or unsuccessful attempts to work may not. This is a common area of dispute, and the wording of your policy governs the answer.
The Legal Framework
TPD claims sit under federal law, meaning they apply equally across Australia. Here are some of the key legal documents worth knowing about:
- Superannuation Industry (Supervision) Act 1993 (Cth) governs how super funds and the insurance held inside them operate.
- Insurance Contracts Act 1984 (Cth) governs the insurance policy itself, including the duty of both sides to act with utmost good faith.
- Treasury Laws Amendment (Putting Members' Interests First) Act 2019 (Cth) removed default insurance for many members under 25 or with low balances from 1 April 2020.
- Treasury Laws Amendment (Protecting Your Superannuation Package) Act 2019 (Cth) cancels insurance on accounts left inactive for 16 months.
What this means for you:
Your eligibility is shaped by the policy wording and by these federal rules about when cover starts and stops.
Furthermore, MoneySmart notes a TPD payout may be taxed at up to 22% if you are under 60, so the lump sum you receive can differ from the sum insured.
When to Get Legal Advice
Some situations are harder to work through alone. Consider getting advice if:
- Your policy uses an any-occupation definition and you are unsure whether you meet it.
- You hold cover across several funds and cannot tell which policy best applies.
- Your account has been cancelled or lapsed near the time your condition arose.
- The insurer has asked for detailed medical or work-history information.
- Your claim has been delayed, disputed or declined. See our guides to the common reasons for TPD claim denials and to the TPD claims process.
Why early advice matters:
Early legal advice can make a significant difference because a TPD claim depends on how well your medical evidence and work history fit your policy's definition of disability.
Insurers assess claims using experienced medical and legal teams, so having a lawyer helps ensure your case is presented as strongly as possible from the outset.
Key Takeaways
Remember these essential points:
- Most Australians hold TPD cover through their super, often automatically and without knowing it.
- The policy definition decides eligibility, and any-occupation is the common, harder test to meet.
- Most policies have a waiting period of 3 or 6 months continuously off work before you can lodge.
- Your injury does not have to be work-related, and cover can sit in old or forgotten funds.
- Check every super account via myGov and confirm the definition and waiting period before assuming you cannot claim.
Get Help Now
If you think you may have a TPD claim, Smith's Lawyers can check your cover and explain your options across all your super funds. We offer clear advice on the best course of action for you.
Contact Smith's Lawyers today for a free case review:
- Call 1800 960 482 for a free, no-obligation consultation about your situation
- No upfront costs: We operate on a No Win, No Fee, No Catch® basis; you only pay if we secure compensation for you
- Or request a call back: Use the form below to have our experienced team get in touch at a time that’s convenient for you.