Yes, you can. Your visa has nothing to do with whether you can claim Total and Permanent Disability (TPD) cover held through an Australian super fund.
Your entitlement is from the group insurance policy and your fund's trust deed. Two things then have to happen before you are paid: the insurer needs to accept the claim, and the trustee needs to be satisfied you meet a condition of release.
Do you actually have TPD cover?
If you have worked in Australia while on a temporary visa, you probably have superannuation.
Whether TPD insurance was attached to it is a separate question, and for younger workers with modest balances the answer is generally no.
The Australian Taxation Office is clear about supers themselves on its page for temporary residents, stating that when you work in Australia, your employer may be required to make super contributions for you, and “generally, this does not depend on your visa (so long as you have work rights) or tax residency status.”
Automatic cover is the insurance a fund gives you without you having to ask, and they usually do so without any health questions. It’s different from TPD.
ASIC's Moneysmart states that insurance through super "does not start automatically if you're a new member under 25, or your balance is under $6,000," unless you ask for it or work in a dangerous job. This catches a lot of student and working holiday visa holders out.
Cover can also be stopped. Funds cancel insurance on accounts where there are no contributions for at least 16 months, and some act even sooner under their own rules. Cover often starts as limited cover, which will only pay for a condition that arose after cover began.
If you have worked for several employers you may have several accounts, and possibly money with the ATO as well. Our guide on finding lost superannuation covers how to trace it in detail.
The two questions that decide whether you get paid
All TPD claims made through super are decided by two tests, which are applied by different decision makers against different criteria. It’s important to understand this as it can prevent you from losing out on a live entitlement.
Neither test is about immigration status.
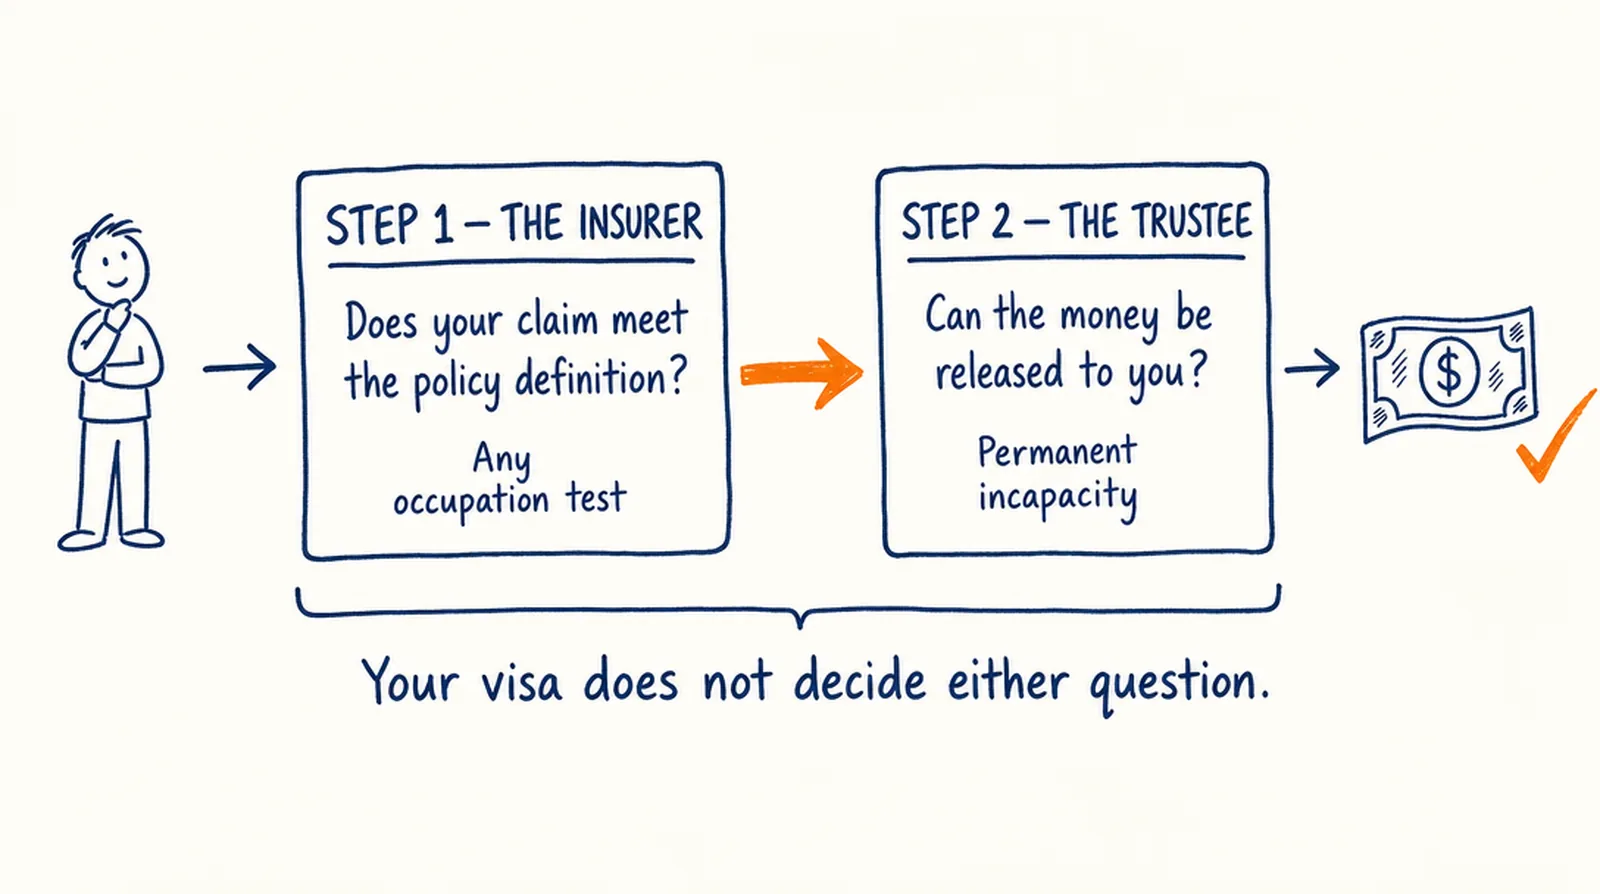
Will the insurer accept the claim?
Insurers measure your case against the TPD definition in the policy.
For superannuation, that is almost always an “any occupation” definition, which Moneysmart describes as being “unable to ever work again in any job suited to your education, training or experience.”
Own occupation cover, which is only to do with the job you were doing, is the easier test, and Moneysmart notes that it “is usually only available outside super.”
Since 1 July 2014 trustees cannot provide an insured benefit unless the insured event lines up with a shortlist of conditions of release. “Own occupation” doesn’t because it can pay someone who could still work in another job. Members who joined a fund before that date may hold grandfathered own occupation cover.
Most policies also have a waiting period before the definition is tested, and getting through it is not the same as meeting the definition.
See our guide to 'own occupation' versus 'any occupation' definitions for more information.
Can the trustee release the money to you?
If the insurer accepts your claim, the benefit is paid into your super account.
It still counts as superannuation, and you can only get it once a condition of release is met. Your trustee decides that separately, under the Superannuation Industry (Supervision) Regulations 1994 (Cth).
For TPD claims, the condition of release is permanent incapacity, so the trustee must be reasonably satisfied that your ill-health, either physical or mental, makes it unlikely you will ever engage in gainful employment for which you are reasonably qualified by education, training or experience again.
Permanent incapacity is a condition of release that temporary residents can meet. Temporary residents are limited to a closed list of release conditions, which includes permanent incapacity.
An accepted claim can generally be paid out while you are still in Australia, so you don’t have to leave the country to get it.
The ATO has the same test plainly on its early access to super page, and adds a point many people find surprising: you may still be eligible for TPD even if you are doing some other work, such as light duties or casual work in another field.
Getting the money while you are here or after you leave
There are two routes to getting the money from a TPD claim. The one which applies to your situation depends on where you are and whether your visa is still in effect, and they are taxed completely differently.
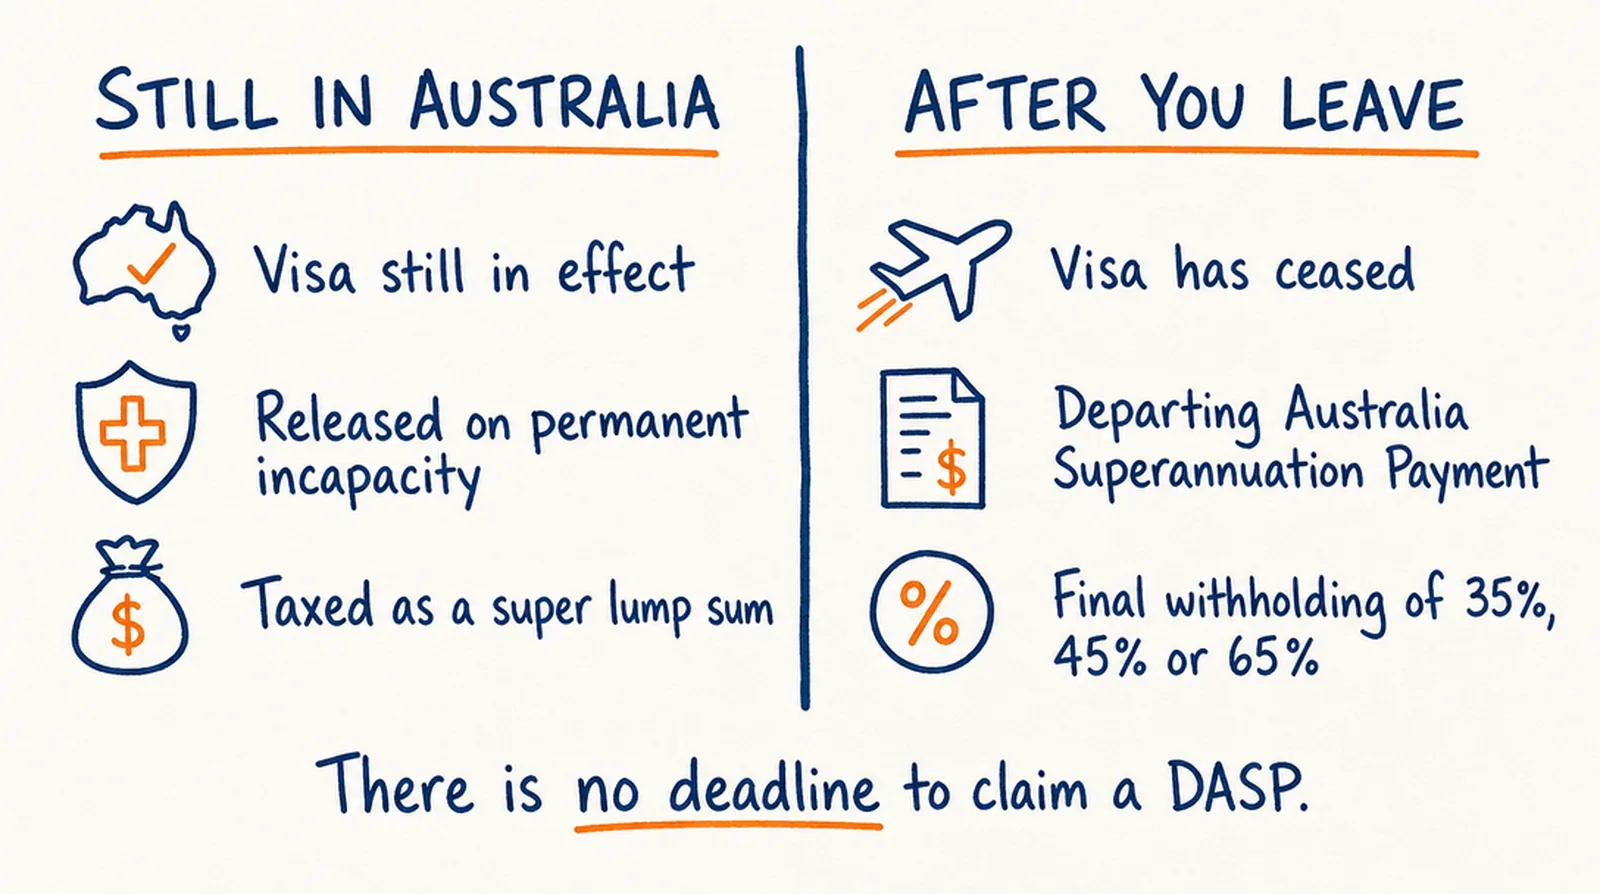
A superannuation lump sum released on permanent incapacity is not automatically tax free.
Below your preservation age, which is now 60 for everyone still under it, tax on the taxed element of the taxable component is capped at 20%, plus the 2% Medicare levy, so 22% at most. The tax-free component is not taxed.
Because TPD benefits are a disability superannuation benefit, part of what would otherwise be taxable shifts into the tax-free component to reflect the working years you have lost.
How much depends on your own dates, so there is no single percentage, and it is not automatic. Two legally qualified medical practitioners must certify your situation here.
Check your payment summary for details.
How DASP works
The ATO's DASP page sets out four requirements, all of which must apply in order for you to claim your super.
They are: you accumulated super working on a temporary resident visa other than subclasses 405 and 410; your visa has ceased; you have left Australia and hold no other active visa; and you are not an Australian or New Zealand citizen or an Australian permanent resident.
You cannot lodge until after you have left, but the ATO recommends starting the application before you go because certifying identity documents is easier while you are still in the country.
There is no deadline. The ATO's ATO-held super page says that if you have not claimed within six months of departing Australia, and your visa expiring, your super is transferred to the ATO as unclaimed super money, and “you can claim your super at any time.”
This changes who holds your money, but it doesn’t take it away from you.
DASP tax is a final withholding you cannot reduce with a tax return.
The working holiday maker rate applies if you have ever held a 417 or 462 visa, or an associated bridging visa, and your payment includes contributions made while you held it.
The ATO is clear about the fact that the 65% rate then applies to the whole taxable component, including super earned on another visa.
Work out which route applies to you, and confirm the tax with the ATO or an accountant before you make your application.
What you need to do
- Tell your fund early, and lodge before you leave if you possibly can. There is no 30-day rule and no fixed lodgement deadline, but this situation doesn’t get easier with time, and Australian medical evidence and insurer-arranged examinations are much harder to organise once you have left the country.
- Get evidence that speaks to the actual test. This means reports from the specialist treating you on whether you are likely ever to work again in any job you are suited to by education, training or experience, not just a certificate saying you are unfit for your old role.
- Ask the insurer for its claim received date. Under the Life Insurance Code of Practice, a subscribing insurer must decide a lump sum claim within six months of that date, or the end of any waiting period if later. The clock doesn’t start when you give the paperwork to your fund, so a claim can feel overdue when it isn’t. If it really is overdue, see our guide on what to do when your insurer is delaying your TPD claim.
- If you are declined, ask for the reasons and the file. The Code requires written reasons, a summary of the information used to make the decision and copies of the documents relied on within 10 business days of your request. If you need an interpreter or translator, the insurer will pay for one.
- Keep your Australian bank account open if a DASP is likely. For ATO-held supers, the ATO will only pay into an Australian account in your name, or by cheque.
- Keep the one time limit that's genuinely enforced in mind: it isn't a claim deadline, it's a precondition on your right to complain to the AFCA later. If you permanently had to stop working because of the condition you are claiming for, the AFCA can only consider a later complaint about the fund's or insurer's decision if the claim itself was made within two years of you permanently stopping work.
Our TPD claims process guide sets out each stage, and this handy article on the common reasons for TPD claim denials covers what usually goes wrong.
Questions people in your position ask
Can I get my super out early for financial hardship or on compassionate grounds?
No. Neither option is available to temporary residents.
Regulation 6.01B sets out the only conditions of release a temporary resident can satisfy, and severe financial hardship and ordinary compassionate release are not among them.
The ATO says the same in its eligibility conditions for compassionate release of super: if you are currently a temporary resident, “you don't meet this condition and you're not eligible to apply.”
What is on the list is permanent incapacity, a terminal medical condition and temporary incapacity, which is only paid out as an income stream and generally needs income protection cover attached to your account.
Will the insurer say I can just work in my home country?
This depends on the policy wording and the evidence, not on where you live. The “any occupation” test is based on whether you are unlikely ever to work again in any occupation you are reasonably suited to by education, training or experience, and nothing in that wording restricts the question to Australia.
Your capacity to work overseas can be relevant, but that does not make it decisive, and it does not mean an insurer can simply assume it to be true.
If that is the reason for your claim being declined, ask for the reasons in writing and the evidence relied on, and have both reviewed before you respond.
The law behind this
- Superannuation Industry (Supervision) Regulations 1994 (Cth), regulation 6.01B(3). The only conditions of release a temporary resident can satisfy: permanent incapacity (Schedule 1 item 103), terminal medical condition (item 102A) and temporary incapacity (item 109) are open. Retirement, turning 65, severe financial hardship and ordinary compassionate release are not.
- SIS Act 1993 (Cth) s 10(1) with SIS Regulations regulation 1.03C defines permanent incapacity in the words used above. Regulation 4.07D is the rule that has kept own-occupation cover out of super since 1 July 2014.
- Income Tax Assessment Act 1997 (Cth) ss 301-35 and 307-145. The lump sum tax cap and the disability benefit uplift described above.
- Life Insurance Code of Practice, March 2025 version, published by the Council of Australian Life Insurers and enforced by the independent Life Code Compliance Committee. It binds subscribing life insurers, not super trustees.
- AFCA Rules, rule B.4.1.1. If you permanently ceased employment because of the condition claimed for, the claim must have been made within two years of that, and the complaint must reach the AFCA within four years of the decision. Otherwise the window is six years. An internal review does not restart that clock, and AFCA will not extend these limits.
When to get legal advice
It’s always a good idea to seek legal advice at the earliest opportunity in cases involving TPD claims on a temporary visa, especially if:
- Your claim has been declined or not decided within six months of the insurer recording receipt.
- You have been told your visa status rules you out.
- The decline turns on a suggestion you could work in your home country.
- Your claim involves a mental health condition. Our guide to making a TPD claim for PTSD, depression or anxiety explains what the test asks.
- You are facing repeated medical examinations or surveillance.
- You have left Australia with a claim still open.
Why early advice is so important here: the two-step structure is where unrepresented claimants come unstuck the most. People take an insurer's acceptance as the end of the matter, and cannot work out why no money has arrived, or they treat a trustee's release decision as an insurance decision and challenge the wrong thing with the wrong body.
A lawyer who runs these claims reads the policy and the trust deed together, and makes sure the evidence ends up where it needs to be.
Key takeaways
Remember these essential points:
- Your visa has nothing to do with whether you can make a claim. Entitlement comes from the policy and the trust deed, and standard policies do not exclude members by visa status.
- Acceptance is not payment. The insurer applies the policy definition, and the trustee separately applies a condition of release. These are different tests, with different decision makers.
- Permanent incapacity is available to you, but severe financial hardship and compassionate grounds are not. Regulation 6.01B puts permanent incapacity on the closed list a temporary resident can satisfy, so an accepted claim can usually be paid while you are in Australia.
- There is no DASP deadline. After six months, your fund transfers the balance to the ATO, and the ATO says you can claim it at any time. What DASP costs you is tax: 35%, 45%, or 65% if you have ever held a working holiday maker visa.
Get Help Now
If you have become seriously ill or injured while working in Australia on a temporary visa, two things are worth knowing: your visa is not a barrier to claiming, and a declined claim is not the end of the matter.
Call Smith's Lawyers on 1800 960 482 for a free, no-obligation discussion with our superannuation insurance claim (TPD) experts.
We work on a No Win, No Fee, No Catch® basis, so there are no upfront costs and you only pay if your claim succeeds.
When you get in touch, we will ask which super funds you held cover through and the date you stopped work, so we can identify which policy applied to you. You can also use the form below this article to request a call back.
We help people nationwide with superannuation insurance claims (TPD), including claims by temporary residents and former visa holders. We do not act in immigration matters, so if your situation also turns on your visa, speak to a registered migration agent.