If you were hurt in a pile-up, you do not have to work out which driver was at fault before making a claim.
Queensland's compulsory third party (CTP) scheme is designed to deal with situations where more than one vehicle may be responsible.
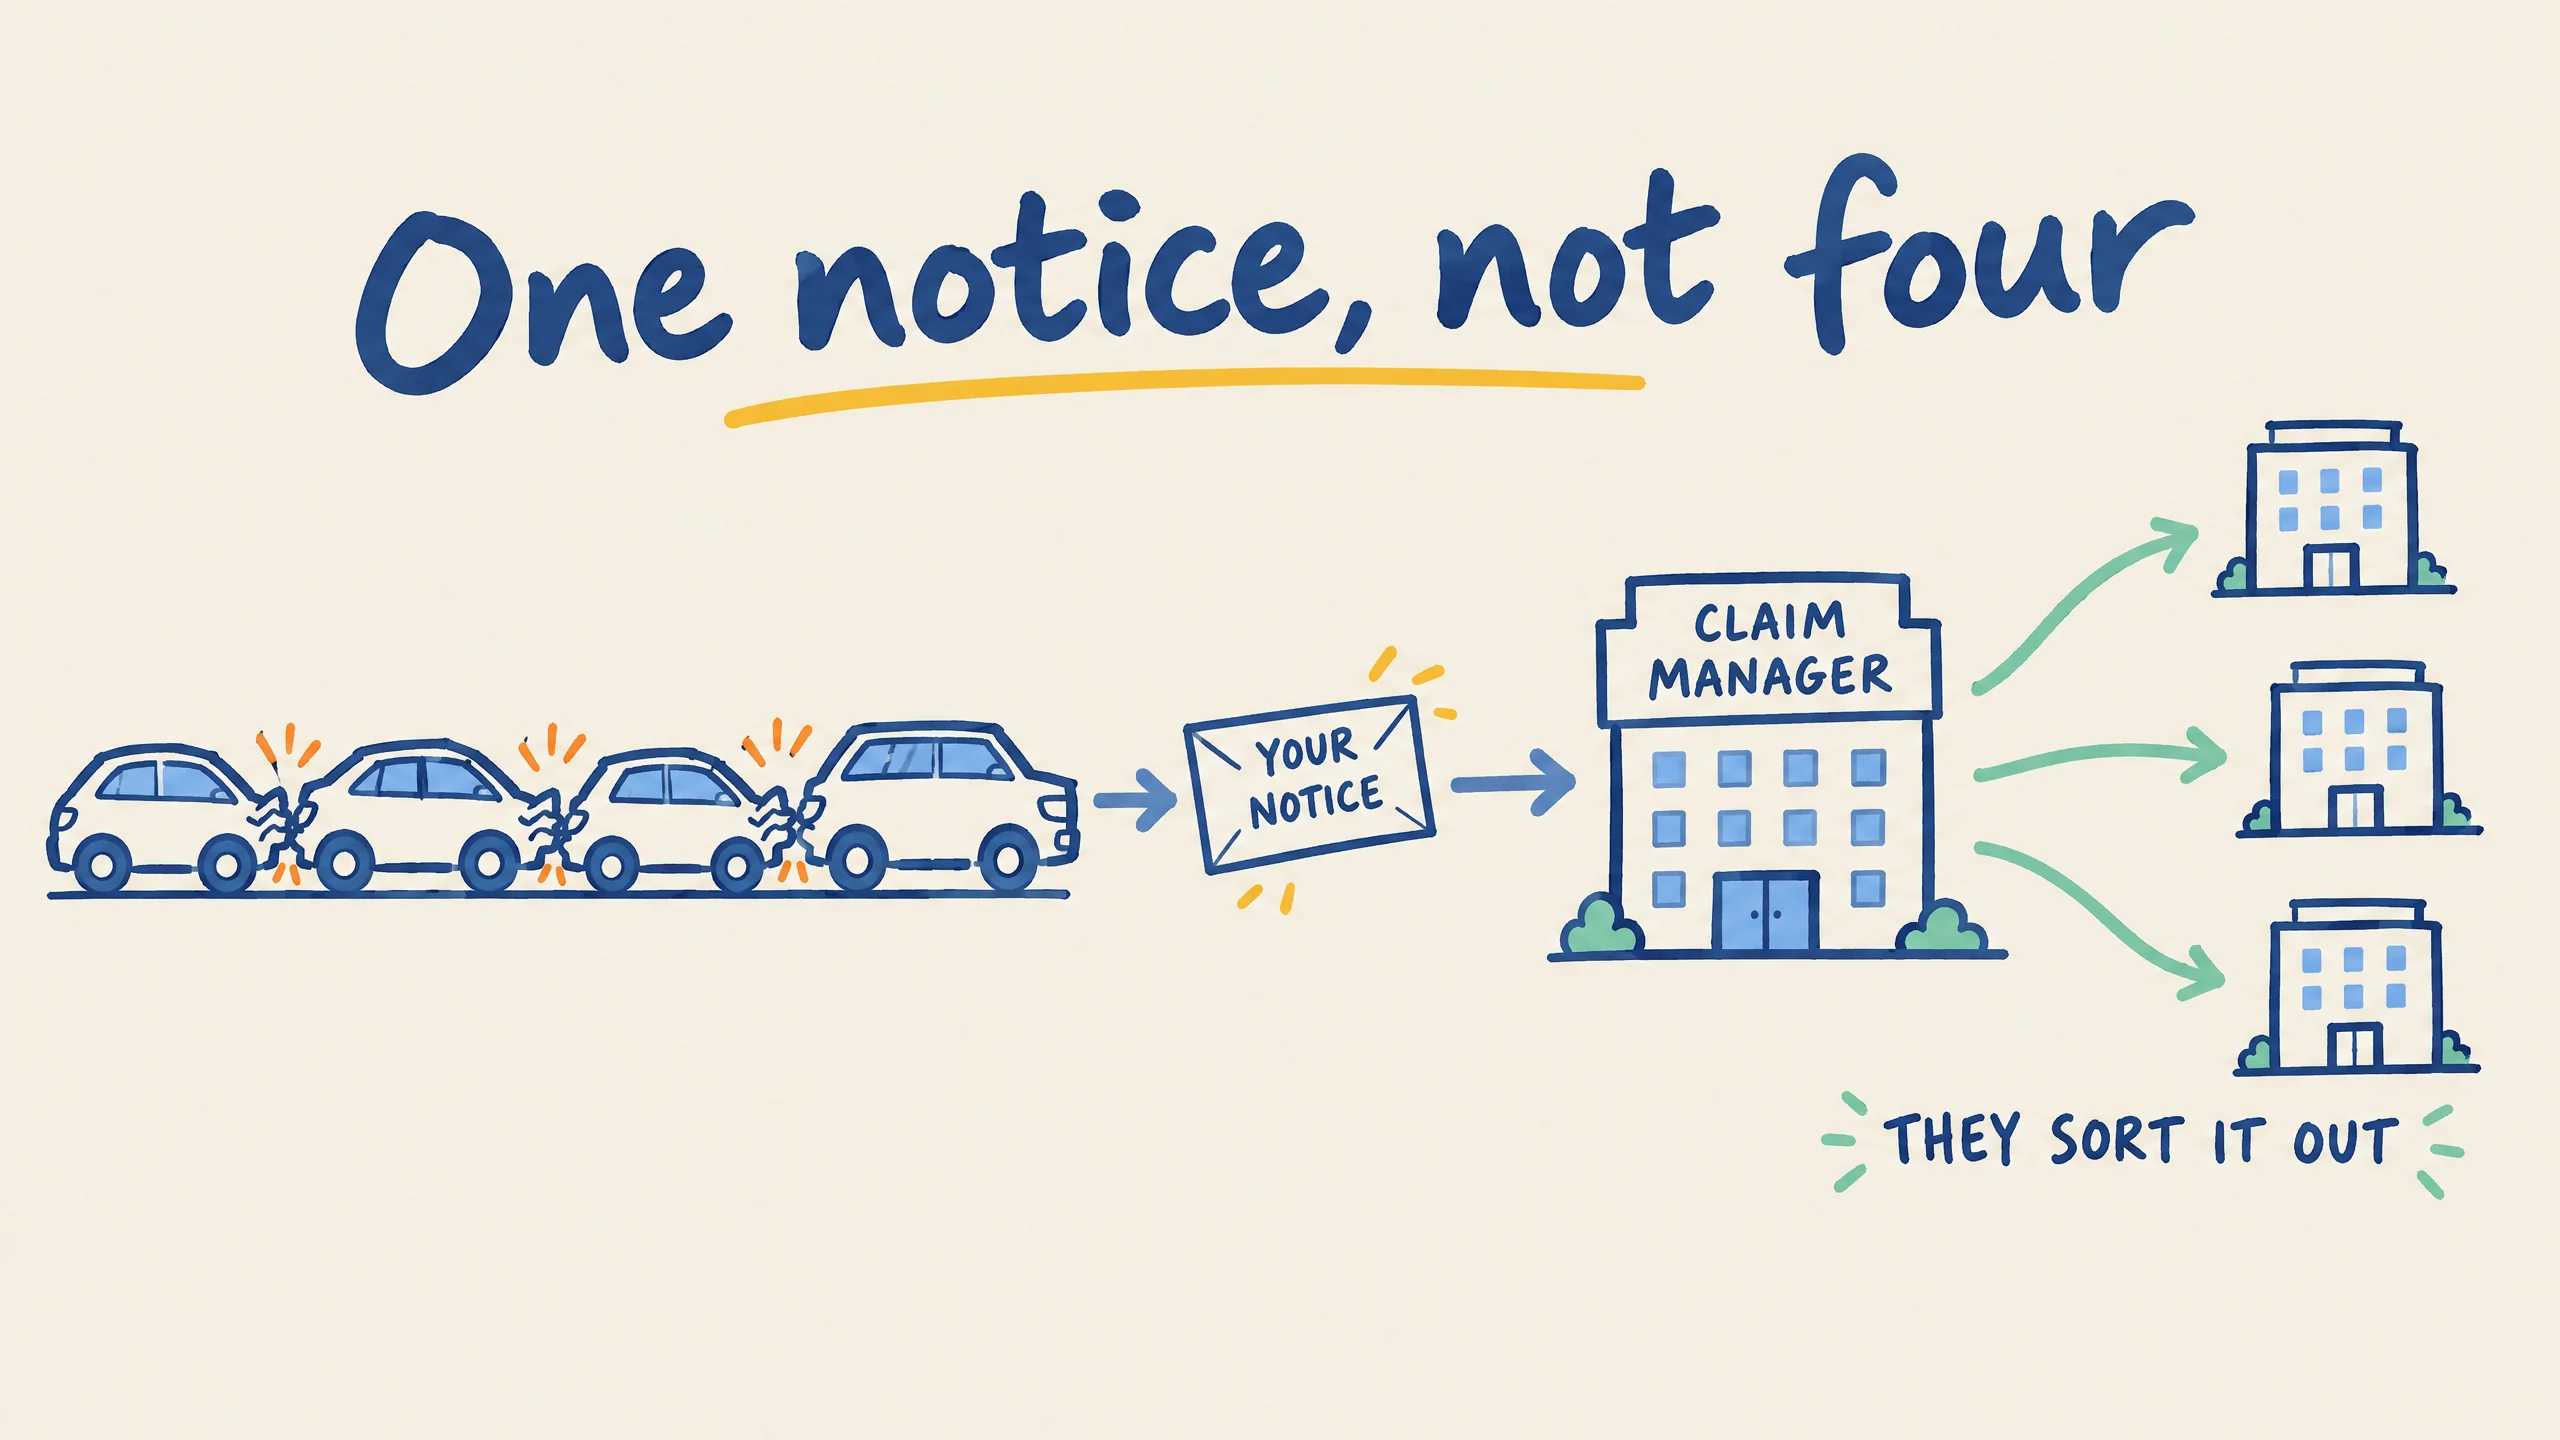
You give notice of your claim to one of the insurers involved. If more than one insurer may be liable, they appoint one of themselves as the claim manager.
The claim manager handles the claim, and the insurers then work out how the liability should be divided between them.
The Thing Most People Get Wrong About Pile-Ups
The common assumption is that you have to identify the driver who caused the crash, then claim against them.
In a chain collision involving four or five vehicles, that feels impossible, and people delay making a claim because of it.
Fortunately, the scheme doesn’t work that way.
What the legislation says
Under section 37(1) of the Motor Accident Insurance Act 1994 (Qld), notice of a claim is given ‘to the insurer or 1 of the insurers’ against which the action is to be brought. That’s it: one insurer.
Section 38(1) is the next step. It confirms that where two or more vehicles are involved and two or more insurers may be liable, one of the insurers becomes the claim manager and acts for all of them.
Three details of section 38 are worth knowing:
- The insurers have 2 months from when notice was first given to agree who the claim manager will be. If they cannot agree, it is decided under the industry deed. This is a deadline for them, not for you.
- Until that is settled, section 38(3) makes the insurer you gave notice to the claim manager by default.
- They must cooperate. Section 38(5) requires the claim manager and the other insurers to share information relevant to the claim. Section 38(4)(c) entitles the claim manager to seek information from other insurers.
One exception. Where the Nominal Defendant is one of the insurers because a vehicle cannot be identified, section 38(6) allows another insurer to act on its behalf. The Nominal Defendant must agree to this in writing.
Section 37(4) puts the responsibility on the insurers, not you. If two or more vehicles were involved, the insurer you notified must, within 7 days, send a copy of your claim notice to every other insurer involved.
That means you do not have to sort out which insurer is responsible before making your claim. The insurers can work out how responsibility should be divided while your claim is being dealt with.
How Fault Is Decided in a Chain Collision
Liability still matters, because it decides which insurers contribute and whether your damages are reduced.
It is decided on the facts of each crash, and in a multi-vehicle collision it is frequently apportioned between several drivers rather than resting on one.
The general principles that apply
A driver who fails to stop in time is generally responsible for the impact they cause. The usual expectation is that you keep enough distance to stop safely, including where the vehicle in front brakes hard.
A vehicle that was pushed is a different matter. If a stationary or slowing car is struck from behind and shunted into the car ahead, the driver of the pushed car did not cause that second impact. The force came from behind them.
A single driver can cause a whole chain. Where one vehicle hits a line of stopped traffic, causing each car to be pushed into the one ahead, the downstream collisions all result from that initial impact.
Several drivers can each be responsible for their own impact. Where each vehicle in a queue independently fails to stop, that is a sequence of separate failures rather than one chain reaction.
Which of these describes your crash comes down to the evidence. Two collisions that look identical from the outside can be decided differently once the braking, spacing and timing are known.
Which Insurer Is Involved
Section 31 of the Act sets out how the insurer is identified for each vehicle:
The last row matters. Sadly, it’s often the case that the driver who caused the chain collision is the one who drives off. Under section 31(2), a vehicle is presumed unable to be identified where it is shown that proper inquiry and search were made and failed.
Note the shorter deadline. Where notice goes to the Nominal Defendant because the vehicle cannot be identified, section 37(2)(a) gives you 3 months from the accident, not 9.
What CTP Does and Does Not Cover
CTP insurance covers personal injury. It does not cover damage to vehicles or property.
Damage to your car is dealt with under your own comprehensive or third-party property policy, or directly with the at-fault driver. That is a separate process from your injury claim and is not covered here.
Common Situations and FAQs
If I was in the middle of a pile-up, am I at fault or not?
The short answer: It depends on whether you struck the car in front under your own momentum or were pushed into it.
What to do: Record the order in which you felt the impacts. Being hit from behind first, then striking the car ahead, is very different from striking the car ahead then being hit from behind.
Important note: Even if you bear some responsibility, you can still claim. It just reduces your damages rather than ending your claim entirely.
If there were five cars involved in the crash, do I have to claim against all of them?
The short answer: No. You give notice to one insurer, and section 38 requires one insurer to act for all of them.
What to do: Give notice as early as you can. Under section 38(3), the insurer you notify first is the claim manager until the insurers agree otherwise.
Important note: If the matter goes to court, section 52(3) provides that where a claim involves two or more insurers, they all become defendants. The claim manager continues to represent them unless the court allows separate representation.
If one of the cars drove off, does that put an end to my claim?
The short answer: No. Under section 31(1)(d), the Nominal Defendant is the insurer where the vehicle or its CTP insurer cannot be identified.
What to do: Report it to the police and give notice within 3 months (section 37(2)(a)).
Important note: The presumption under section 31(2) requires a proper inquiry and search. You therefore need to make a genuine effort to identify the vehicle and keep a record of what you did (inquiries with the police/MAIC’s online tools).
Who do I claim against if I was the passenger?
The short answer: The same scheme applies. As a passenger, fault normally rests with one or more of the drivers, and your claim proceeds against the insurer of whichever vehicle or vehicles were responsible.
What to do: Give notice as you normally would. You do not need to choose between drivers.
Important note: This includes being a passenger in a vehicle whose driver was at fault.
What happens if the other drivers are blaming each other for the accident?
The short answer: That dispute concerns the insurers. Section 38 exists precisely so that it does not stall your claim.
What to do: Give your account of what happened once, state it clearly, in writing, and keep it consistent should you need to give further details down the line.
Important note: Do not wait for the insurers to agree before lodging. The notice deadlines run from the accident, not from the resolution of their argument.
How long do I have to make a claim?
The short answer: Notice is due 9 months after the accident (or when the first symptoms arise) or 1 month after first consulting a lawyer. It is 3 months when the vehicle cannot be identified. Court proceedings must generally start within 3 years.
What to do: Treat the notice deadline as the important deadline. The 3-year limitation period under section 11(1) of the Limitation of Actions Act 1974 (Qld) is separate and generally runs much later.
Important note: Missing a notice period does not automatically end your claim. Under section 37(3), the obligation to give notice continues, and you must give a reasonable excuse for the delay. However, where the vehicle cannot be identified, and notice is not given to the Nominal Defendant within 9 months of the accident, the claim against the Nominal Defendant is barred outright.
Steps to Take After a Multi-Vehicle Crash
- Get medical attention and tell the doctor it was a motor vehicle accident, so the cause is on record from the very start.
- Write down the sequence of impacts while it is fresh in your memory: how many you felt, the intensity, or any visual information you recall.
- Record every vehicle you can, including registration, make, colour and position in the line.
- Photograph the scene before vehicles are moved, showing positions, damage and road conditions.
- Get witness details, especially from anyone in a vehicle that was not involved.
- Report to the police, particularly if any vehicle left the scene.
- Give notice of your claim to one of the insurers involved.
Documents You Will Need
- Your medical records from the date of the crash: establish the injury and its cause.
- Police report or event number: independent record, and essential where a vehicle left the scene.
- Photographs of vehicle positions and damage: the primary evidence of the impact sequence.
- Details of every vehicle involved: registration numbers, in particular, are vital for the insurer's process of identifying the drivers involved.
- Witness contact details: a non-partisan witness carries particular weight when it comes to multi-vehicle accidents.
- Your own written account, made early: the full details of the event will fade fast, even within a couple of days.
Legal Framework
Most of the relevant provisions come from the Motor Accident Insurance Act 1994 (Qld):
- s 5: sets out when the Act applies, including where the injury was caused wholly or partly by someone other than the injured person.
- s 31: sets out the principles for determining which insurer is involved, including when the Nominal Defendant is involved because a vehicle is uninsured or unidentified.
- s 37: covers the notice of accident claim, including who must receive it and the applicable time limits. Subsections (3) and (4) also deal with reasonable excuses for late notice, the 9-month time limit for unidentified vehicles, and the insurer's obligation to notify other insurers.
- s 38: deals with multiple insurers, including the appointment of a claim manager and the insurers' obligation to cooperate.
- s 52: provides that where a claim lies against two or more insurers, they all become defendants and the claim manager represents them.
The Civil Liability Act 2003 (Qld) also applies to issues such as negligence, contributory negligence and the assessment of damages.
The Limitation of Actions Act 1974 (Qld), s 11(1), generally requires proceedings to be started within 3 years of the date the cause of action arose.
What this means for you: the scheme is designed to prevent a multi-vehicle crash from becoming a multi-claim problem for the injured person. One notice starts the process, and the insurers should sort out responsibility between themselves.
Red Flags: What to Look Out For
- You are told to claim separately against each vehicle.
- You are being asked to wait until the insurers agree on fault before lodging.
- A vehicle left the scene and nobody has reported it to the police, with a 3-month deadline looming.
- You are told you have no claim because you hit the car in front, without anyone asking whether you were pushed.
- Nine months are approaching and no notice has been given; if the vehicle cannot be identified, this is an absolute limit.
Common mistakes to avoid:
- Waiting for the insurers to sort out fault before lodging. The deadlines run regardless.
- Assuming that hitting the car in front makes you responsible for that impact, when you were pushed into it.
- Not recording the order of impacts, which is the single fact that decides these cases and the one people often tend to forget.
- Assuming a passenger has no claim.
- Treating the 3 year limitation period as the deadline, when the various notice periods are far shorter.
When Seeking Legal Advice Is Important
Get advice if:
- You are unsure whether you struck the vehicle ahead or were pushed into it
- A vehicle left the scene or is uninsured
- The insurers are disputing fault between themselves
- You have been told you were partly responsible
- You were a passenger and have been given conflicting information about who to claim against
- Any of the notice deadlines are approaching
Why early advice matters:
A pile-up can involve several drivers, insurers and competing accounts of what happened. Although you don’t need to work all of that out yourself before making a claim, getting advice early can help you avoid mistakes that are harder to fix later.
The evidence can also become harder to establish with time. Your memory of the impact sequence can fade, vehicles are repaired or moved, and witnesses can become harder to contact. Getting advice early gives you a chance to preserve that evidence while it is still available.
Important note: When you first consult a lawyer, the notice period becomes just 1 month under section 37(2)(b). For a proficient legal team, this shouldn’t be an issue, and they should make you fully aware of how the timeline may shift.
Key Takeaways
Remember these essential points:
- You lodge one claim, not one claim per vehicle. Section 37(1) allows notice to one insurer.
- Where several insurers may be liable, one acts for all of them as claim manager under section 38.
- A vehicle that was pushed is generally not the cause of the impact in front of it. That distinction decides many pile-up claims.
- An unidentified vehicle does not end your claim, but it gives you a shorter 3-month notice period. An identified but uninsured vehicle is different: the claim can still go through the Nominal Defendant, but the ordinary 9-month notice period generally applies.
- Partial fault reduces compensation rather than disallowing the claim. Section 5(1)(b) requires only that someone other than you was wholly or partly at fault.
Get Help Now
If you were injured in a multi-vehicle crash, we can tell you which insurer to notify, what your deadline is, and what the impact sequence means for your claim.
Call 1800 960 482 for free initial advice. We operate on a No Win, No Fee, No Catch® basis.
You can also use the form below this article to request a free case review.
When you call, we’ll ask how many vehicles were involved, where you were in the pile-up, and the order in which you felt the impacts. Following this, a member of our team will help guide you on the best course of action to take.