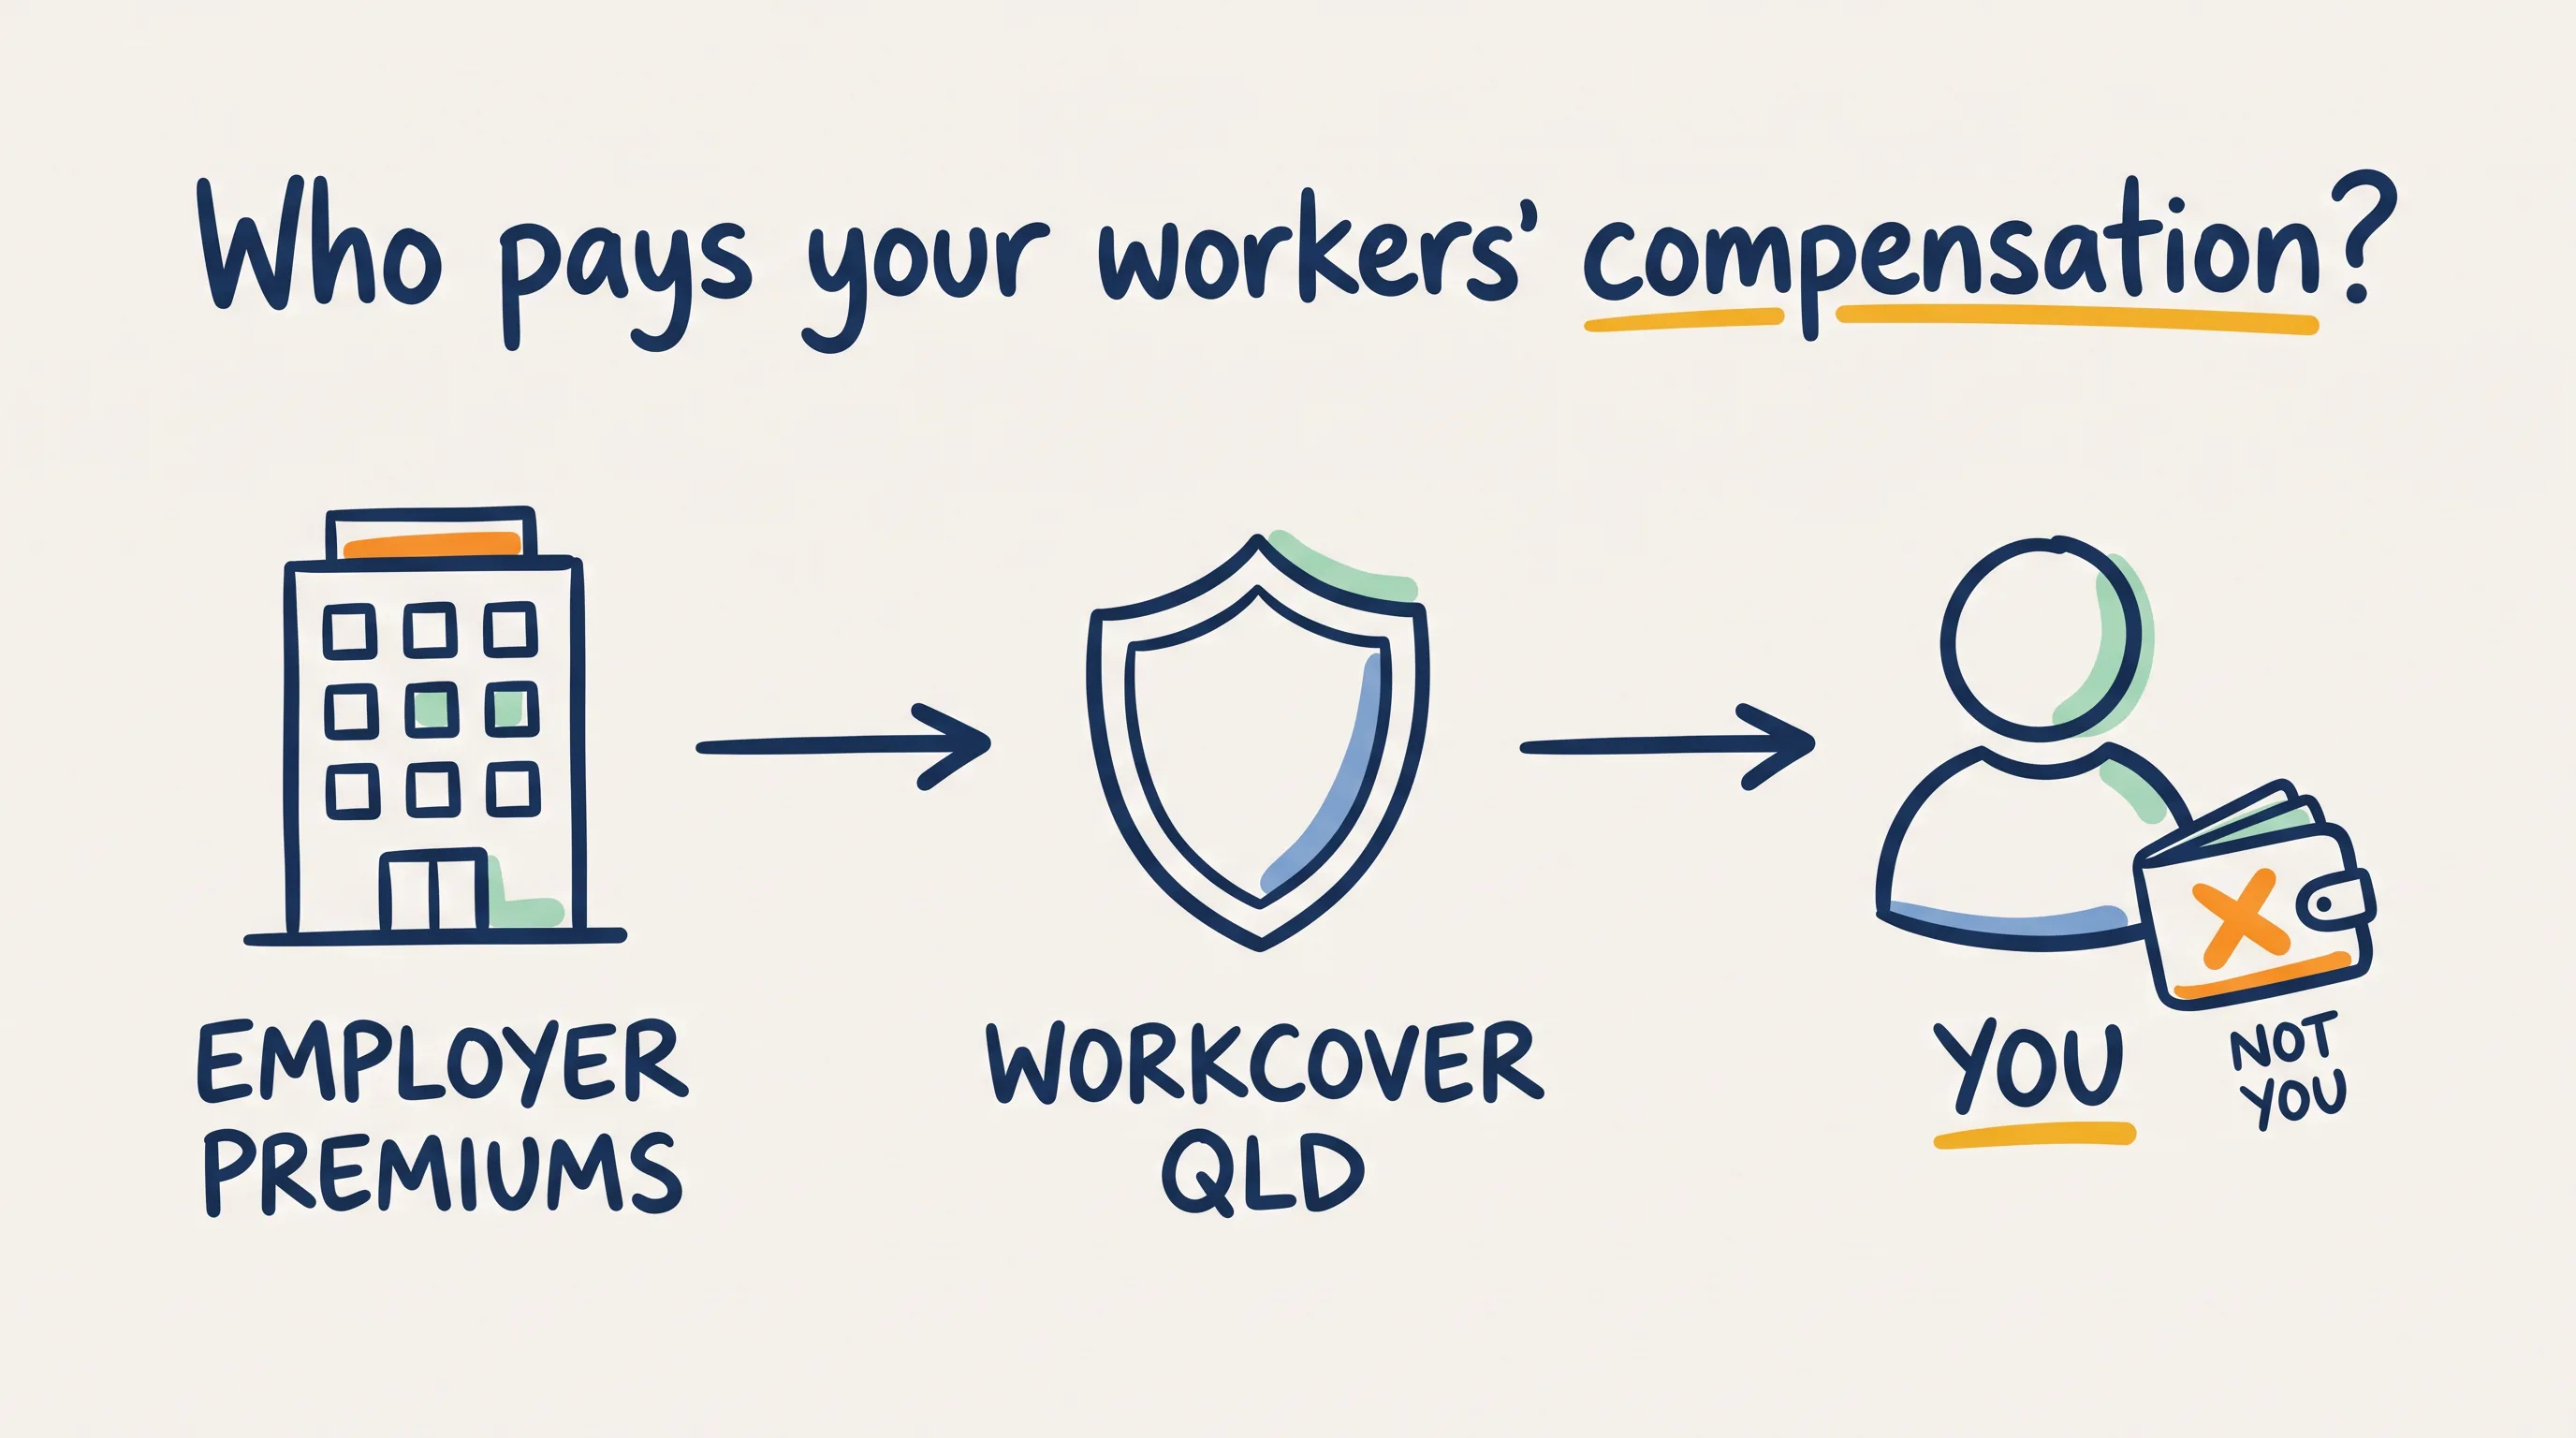
In Queensland, your employer pays for your workers' compensation, not you.
Most employers fund this compensation through WorkCover Queensland accident insurance policies, which are paid for entirely by employer premiums. Certain employers are licensed self-insurers who fund claims directly instead, but these are very low in number and generally only very large companies.
Either way, injured workers never have to pay for their own claim, nor will they be asked to contribute to the premium.
Understanding who funds a workers' compensation claim
Queensland runs a no-fault statutory scheme, which means that injured workers who are eligible receive support regardless of who caused the injury. That support is paid for by the employer's insurance, not the worker.
There are two ways Queensland employers are covered. The vast majority hold a policy with WorkCover Queensland, and a small group of very large employers self-insure.
WorkCover Queensland (the default)
WorkCover Queensland is a government-owned, fully self-funded statutory insurer.
Funding comes from premiums paid by employers, and according to WorkSafe Queensland, it has one of the lowest average premium rates in Australia.
Most Queensland employers use this method for cover. When you lodge a claim, WorkCover Queensland assesses what happened and pays your medical costs, lost wages and for rehabilitation.
Employer premiums are based on the risk involved with the industry they operate in, claims history and total wages.
That premium is paid by employers, never workers.
Self-insured employers
Certain large organisations are licensed to self-insure, which means they fund and manage their own workers' compensation claims rather than paying premiums to WorkCover Queensland.
Self-insurance is available for Queensland employers with at least 2,000 workers.
Self-insurers are obligated to provide the same statutory benefits that WorkCover does. Compensation comes from the employer directly rather than from a WorkCover policy, but your entitlements are not reduced because your employer self-insures.
You can learn more about this in our guide to WorkCover Queensland versus self-insurers.
WorkCover-insured vs self-insured: what changes for you
Even if the source of funding changes, your core rights do not.
These are the practical differences:
Your rights and what the money covers
Whether your employer goes through WorkCover or is self-insured, statutory claims cover the same categories of support.
What you're entitled to:
- Weekly payments to replace lost income. WorkSafe Queensland sets these payments at 85% of your normal weekly earnings for the first 26 weeks, then 75% after that.
- Medical and hospital expenses related to your injury.
- Rehabilitation payments in support of your recovery and return to work.
- A lump sum if you're left with a permanent impairment.
What you must do:
- Report the injury to your employer as soon as possible.
- See a doctor and get a work capacity certificate.
- Lodge your claim so you can start receiving payments.
For a full breakdown of the different types of payment, see our workers' compensation benefits guide.
Who pays a common law claim?
Statutory WorkCover claims are always the starting point, but if your injury was the result of your employer's negligence, you may also be able to pursue a separate legal claim through a lawyer in addition to your statutory benefits.
Common law claims are paid by the same insurer that covers your employer, it will never have to be funded by a worker.
At Smith's Lawyers, any claim is covered by our No Win, No Fee, No Catch® promise, so there is no upfront cost to start.
Common questions
Do I have to pay anything towards my claim?
No. Workers will never be charged a premium, nor will they have to pay for their own statutory claim. Costs are covered by the employer's insurance, so you can lodge a claim without having to pay anything upfront.
What if my employer says they can't afford it?
Your claim is paid by the insurer, not out of your employer's pocket. For a WorkCover-insured employer, WorkCover Queensland pays you directly, so your employer's cash flow won’t prevent payments.
Does it cost me more if my employer is self-insured?
No. Self-insured employers are obligated to provide the same benefits as WorkCover. The source of funding may be different, but the cost to you is still zero.
What if my employer didn't have insurance at all?
You can still make a claim. WorkCover will pay you and then recover the money from your uninsured employer. The employer, not you, carries liability for injuries.
If your employer was uninsured
As per the Workers' Compensation and Rehabilitation Act 2003 (Qld) section 48, every Queensland employer has to hold WorkCover accident insurance, unless they are a licensed self-insurer.
Watch for these signs:
- Your employer tells you there is "no cover" for your injury.
- You're asked to pay medical bills yourself and claim them back later.
- You're pressured not to lodge a claim.
- Your employer asks you to contribute to a premium or excess.
Common mistakes to avoid:
- Assuming no insurance means you have no claim. This is not true.
- Paying medical costs yourself without first seeking advice.
- Delaying your report because you're unsure who pays.
An employer that doesn’t have insurance will have to repay WorkCover for any compensation paid out, in addition to a penalty of 50% of that amount.
That liability falls on the employer, not the injured worker.
When to get legal advice
It’s always a good idea to seek legal advice at the earliest opportunity, especially if:
- Your employer or their insurer disputes or delays your claim.
- You're being told there's "no cover" or asked to pay costs yourself.
- Your employer is self-insured and you're unsure your entitlements are being met.
- Your injury may have been caused by negligence, which can support a common law claim.
Why early advice matters: insurers will almost certainly negotiate differently with a worker who has a lawyer. This is because a represented worker can credibly take a common law claim to court if the insurer doesn’t make a fair offer.
Key takeaways
Remember these essential points:
- Your employer pays, not you. Workers are never charged a premium or asked to fund their own claim.
- WorkCover Queensland covers most employers and pays your claim directly.
- Self-insured employers fund claims themselves but must provide the same benefits.
- Common law claims are paid by the same insurer, and Smith's Lawyers handles all cases under a No Win, No Fee, No Catch®, so it’s always worth exploring a potential common law claim.
- An uninsured employer won't prevent your claim as WorkCover can pay you and recover from the employer.
Get help now
If you've been injured at work in Queensland and you're unsure who pays or how to start a compensation claim, Smith's Lawyers can help. Call 1800 960 482 or request a free case review using the form below, and we'll explain your options in plain English.
There's no upfront cost and no risk to start. Our workplace injury service runs on a No Win, No Fee, No Catch® promise Queensland-wide from our Brisbane and Gold Coast offices.