A WorkCover claim is the no-fault scheme that pays your wages and medical costs while you recover from illness or injury.
A common law claim is a separate claim for damages against your employer, and you will have to prove they were negligent in order to succeed.
The two are not separate options that you choose between on day one; the choice arrives when your notice of assessment lands, and hinges on whether your Degree of Permanent Impairment (DPI) is 20% or more.
What each claim actually is
The statutory WorkCover claim
A statutory claim is the no fault aspect of the Queensland scheme. You have to show your injury arose out of, or in the course of, your employment, and that employment was a significant contributing factor to the injury.
You must lodge the application within 6 months of your entitlement to compensation arising, which is the day a doctor assesses your injury, not the day the accident occurred.
The common law claim
A common law claim is a claim for damages, which is money your employer is legally liable to pay you independently of the Workers' Compensation and Rehabilitation Act. It is a negligence claim, and the burden of proof sits on you.
Section 305B of the Act sets out three tests: the risk had to be foreseeable; the risk had to be not insignificant; and a reasonable person in your employer's position would have taken the precautions.
Section 305E puts the onus of proving causation on the worker, as set out by WorkSafe Queensland.
Where the notice of assessment sits
Once your injury stabilises and is not likely to improve with further treatment, it can be assessed for a Degree of Permanent Impairment.
If you lodged a statutory claim, you or the insurer can ask for that assessment. If not, the insurer then has 10 business days from receiving it to give you a Notice of Assessment (NOA), which sets out your DPI and any lump sum offer. An NOA is what entitles you to seek damages.
The most important exception to this is a terminal condition, which opens access to damages without a notice of assessment at all.
WorkCover claim vs common law claim
The 20% rule and what accepting forecloses
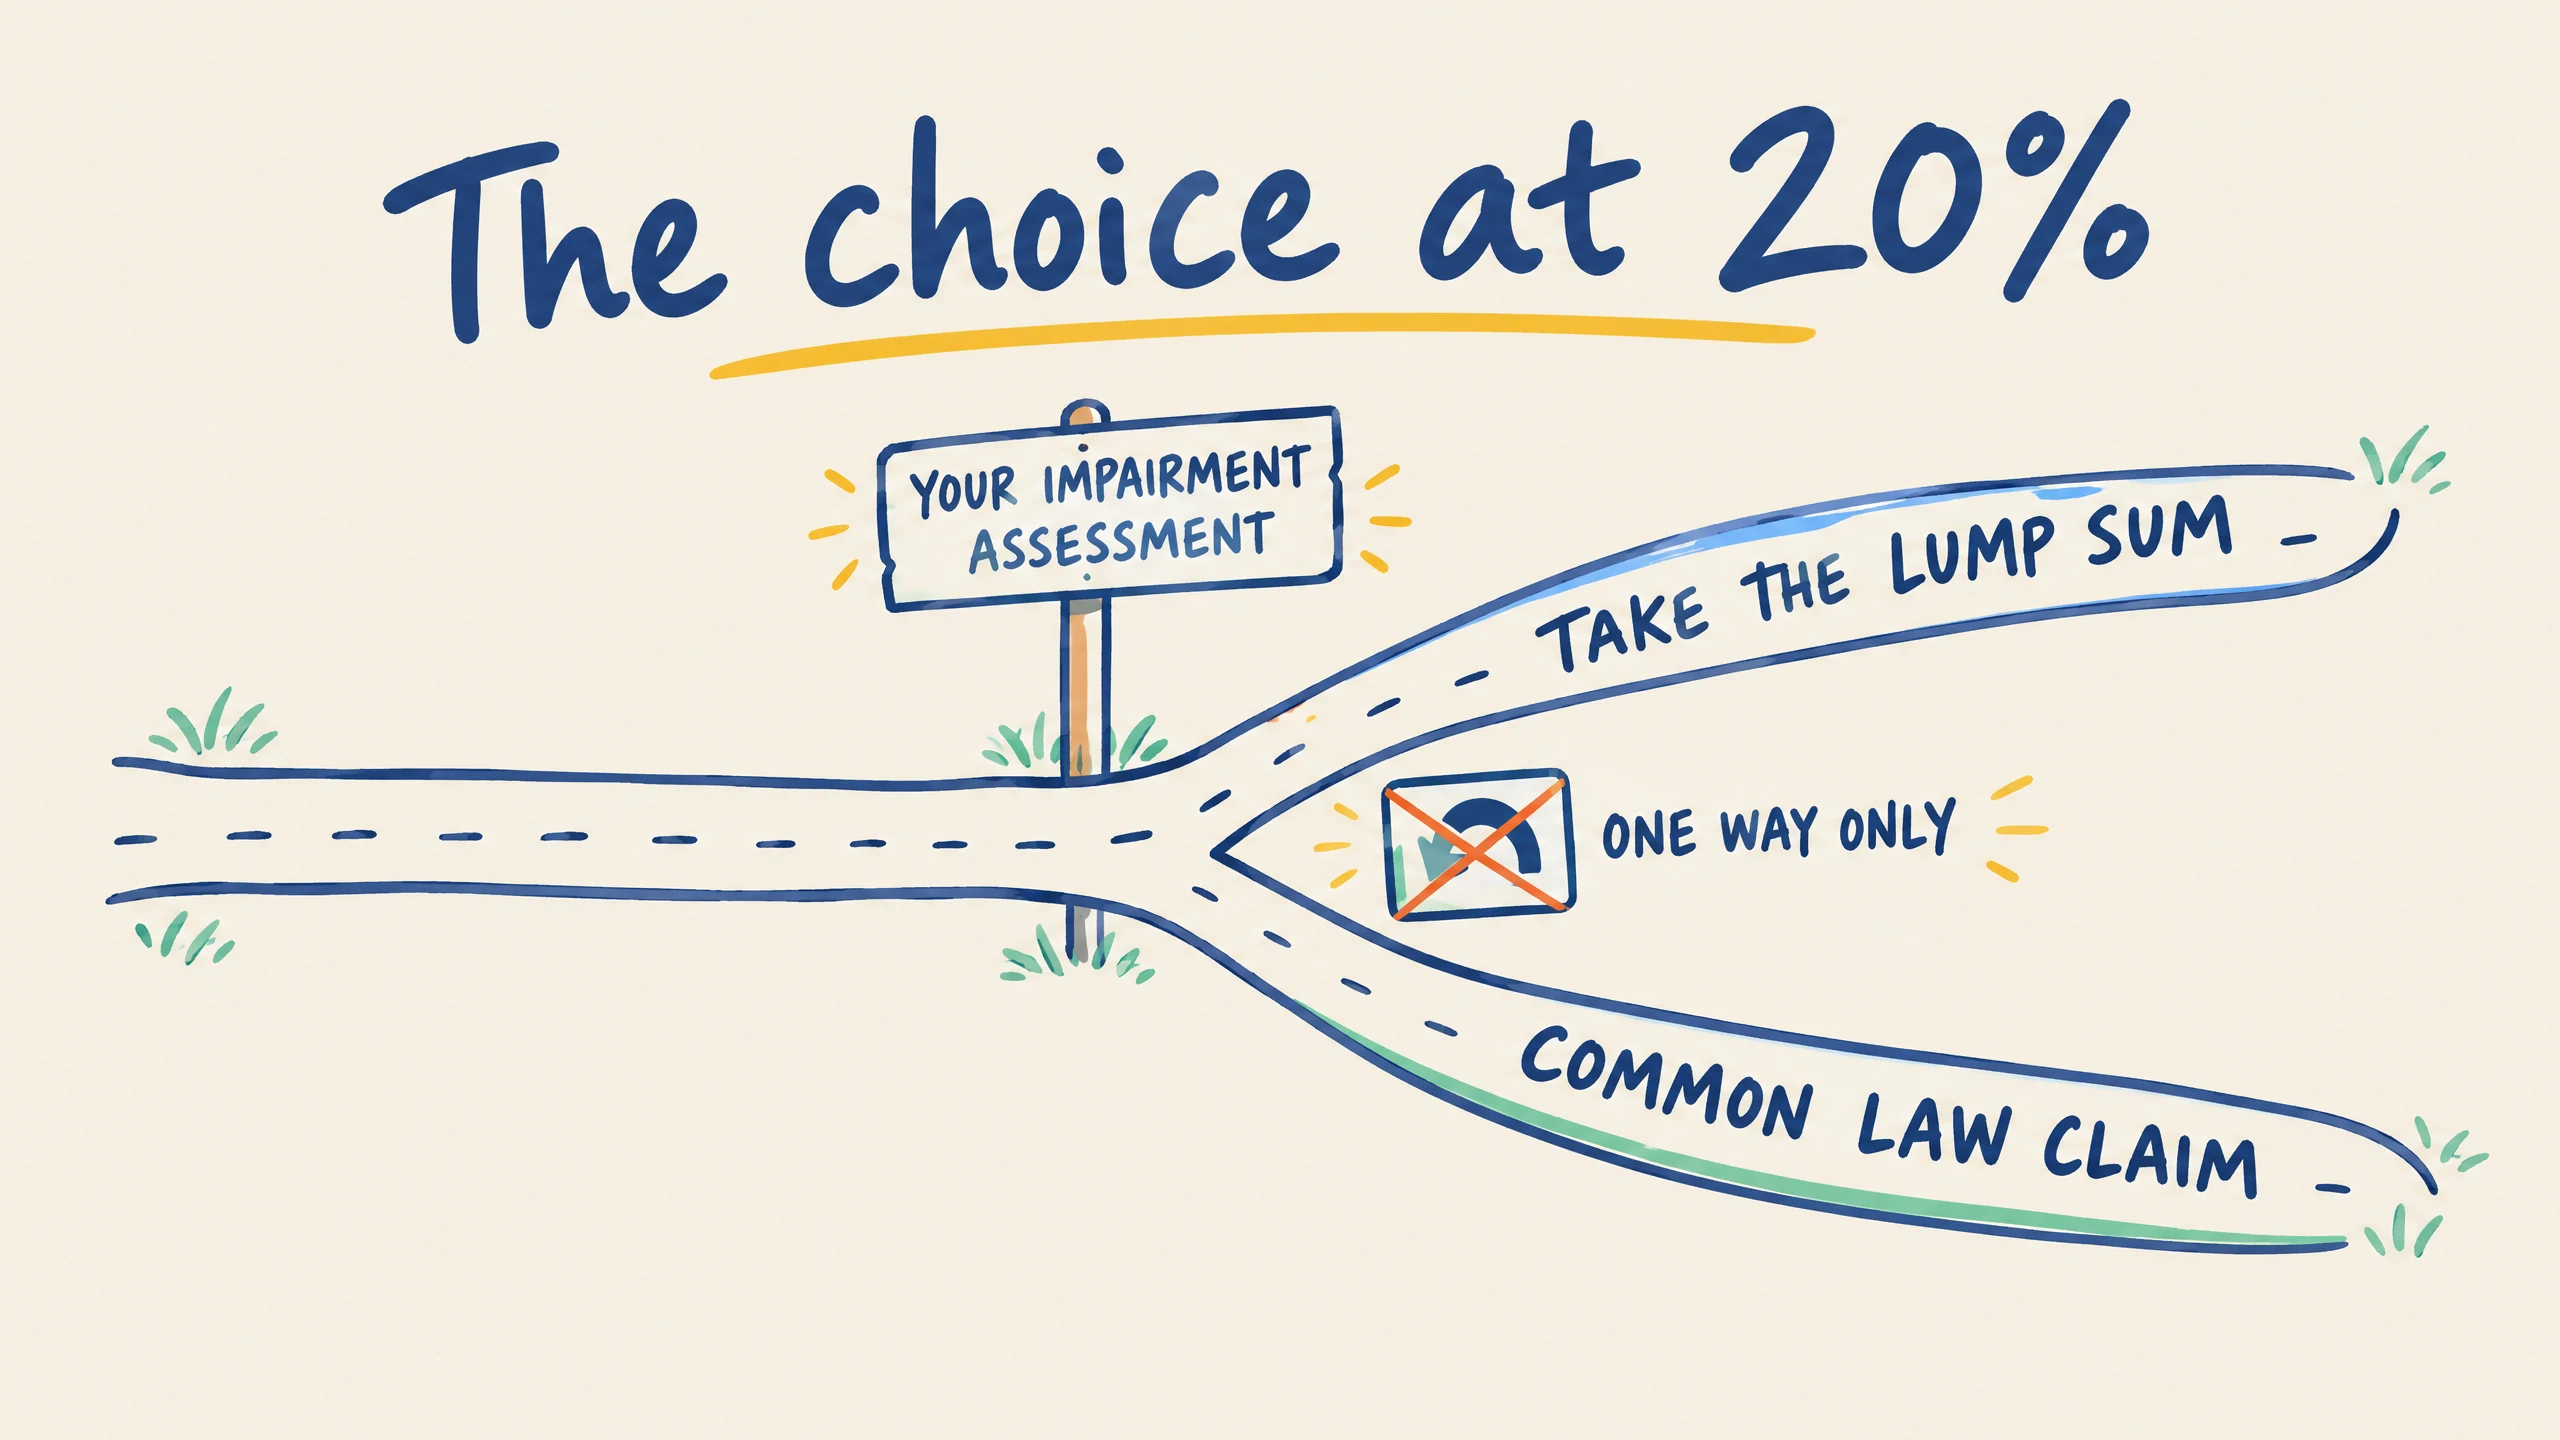
Everything hinges on the DPI figure; if it’s below 20% you have to choose, and if it’s 20% or more you do not.
If your DPI is under 20%
Section 189 of the Act applies if your DPI is 20% or below, including in cases where the assessment comes back at no DPI.
Queensland has no minimum impairment threshold, and a 0% assessment just means there is no lump sum to weigh against a claim. The insurer must tell you that you are making an irrevocable choice between the lump sum and damages.
A worker who was required to make a choice and accepted is not entitled to seek damages.
You have three responses inside the window: accept, reject or defer. If you don’t say anything, you are considered to have deferred. If you lodge a notice of claim without ever giving notice of your election, you are considered to have rejected the lump sum.
If your DPI is 20% or more
If your DPI is 20% or above, section 188 of the Act applies and there is no choice to make. You can accept the lump sum and still pursue a common law claim, or defer the decision.
This does not mean that you get both payouts on top of each other. Any damages are reduced by the total amount of compensation already paid, or is payable for the injury, so the lump sum simply arrives earlier.
There’s one point which often catches people out here. If you have both a physical and a psychiatric injury from the same event, they are required to be assessed separately, which means you end up with two DPI figures which are never combined.
The 20% test is then applied to each figure on its own. WorkSafe Queensland puts the result plainly: "Different impairments cannot be combined to reach 20%."
This means a worker at 14% physical and 11% psychiatric has two sub-20% assessments, not one at 25%.
Before you respond to the notice
- Diarise the 20 business days. It runs from the day the notice is given, not the day you open the envelope.
- Challenge a low DPI inside that same window. Under the Act, you can tell the insurer you disagree with their verdict and ask for either a fresh assessment by a different entity you both agree on, or that the insurer refers the question to a medical assessment tribunal. If the insurer agrees to a reassessment, the original notice is treated as never having been given. This route is not available if a tribunal performed your assessment in the first place.
- Check that nothing is missing. The insurer is required to wait until the DPI for every injury from the event has been decided, so one notice should cover all of them.
- Expect your statutory benefits to stop either way. Weekly payments and medical entitlements will end either when you notify your decision or 20 business days have passed since you received the offer (whichever is first).
What running a common law claim involves
The pre-court steps are statutory, and each starts a clock.
- Lodge a Notice of Claim for Damages with the insurer in the approved form with your notice of assessment attached, and anything within your own knowledge verified by statutory declaration. The insurer has 10 business days in which to say whether it complies, and no response means it does.
- The insurer answers on liability, then you meet. They have 6 months from a complying notice to admit or deny your claim in writing, or 3 months for a worker with a terminal condition. A compulsory conference follows within 3 months of that notice, and you must attend and take part in this conference.
- Final offers, then court. If there is no settlement, each party makes a written final offer at the conference, open for 10 business days. Any proceeding must start within 60 days of the conference, unless the court allows for longer.
How the time limits interlock
Under the Limitation of Actions Act 1974 (Qld), the limitation period is 3 years from the date the cause of action arose, and your notice of claim must be given inside this window.
Extra time can be added in two situations: if a notice of assessment arrives less than 6 months before the limitation period ends, and if you asked for an assessment before that point but have not yet received the notice.
Both situations give you 6 additional months from the notice of assessment, or 6 months from the tribunal's decision if you’re disputing the DPI.
A personal injury stemming from a dust-related condition is not subject to any deadline or limitation period, with silicosis and asbestosis common examples of this situation.
Common questions
Do I have to lodge a WorkCover claim first?
Not as a matter of law. In practice, almost every common law claim runs off one.
The law first. Damages are decided by a notice of assessment, not on a statutory claim. If you have never lodged one, you can apply to the insurer directly for a DPI assessment, and it has 40 business days to make a decision. WorkSafe Queensland says the same: workers do not need a statutory claim to seek a common law claim.
Applications do not entitle you to any compensation, so there are no weekly payments and no lump sum while you wait, and you still have to be assessed.
If you didn’t lodge a statutory claim, or yours was rejected, your options are narrower than the general picture here and the deadlines are already running, so speak to a lawyer as soon as possible.
What happens if I accept the lump sum and then get worse?
There is one narrow statutory review, and it is not a second chance. You can ask the insurer to consider fresh medical evidence of a further material deterioration, as long as you can show that there was no reason to expect that deterioration when the DPI was decided and that the evidence was unavailable at that point.
The thresholds are what make it narrow. The deterioration has to add 10% or more to your DPI, and the new total has to reach 20% or more. The request for a review has to be made inside the limitation period, and the review panel's decision on the evidence is final.
Treat an accepted offer as the claim being closed permanently, which is how WorkSafe Queensland looks at it.
I was hurt driving to work, does that change things?
This changes which claim is realistic, not which claim you actually have. A journey between your home and workplace is inside the statutory scheme, and employment need not be a contributing factor.
Certain journeys are removed from the scheme if drink or drug driving, or dangerous operation of a vehicle, were a major significant factor to the cause of the event.
A substantial delay before the journey, or a substantial interruption/deviation from it, could also have an effect, unless the reason was connected with your work or beyond your control.
Whether you also have a common law claim is a separate question about your employer's duty.
When to get legal advice
It’s always a good idea to seek legal advice at the earliest opportunity in cases such as these, especially if:
- You have a notice of assessment with a DPI under 20% and a lump sum offer attached, or the DPI is lower than your treating doctors' reports suggest.
- You have both a physical and a psychiatric injury from the same event.
- Something points at the employer, such as missing training, a known hazard, faulty equipment and/or an unsafe system of work.
- You are approaching the 3 year deadline and are yet to lodge a notice of claim.
Why early advice matters here: the Section 189 election is irrevocable once notice reaches the insurer, so even good advice you receive afterwards cannot undo it.
Costs also work differently for DPI below 20%. Section 316 of the Act bars any costs order except those it allows, and if the award lands between the two written final offers, each side bears its own.
The exceptions cut both ways, and neither are discretionary. If the court awards you the same or more than your own written final offer, it must order the insurer to pay your costs from the day of that offer. If it dismisses your claim, makes no award or awards no more than the insurer's final offer, it must order you to pay the insurer's costs from the day of that offer.
The law behind this
- The Workers' Compensation and Rehabilitation Act 2003 (Qld) governs both claims. Access to damages sits in chapter 5, which holds the election (s 239), the entry requirement (s 237), the pre-court steps (ss 275 to 302) and the negligence rules (ss 305B to 305H). WorkSafe Queensland publishes the regulator's own guidance on who is at fault.
- Limitation of Actions Act 1974 (Qld) s 11 sets the 3 year period, and s 11(2) removes it for dust-related conditions.
What this means for you: these deadlines and the election are statutory, not matters of goodwill.
Also read: How long do WorkCover payments last?
Key takeaways
- The notice of assessment is the decision point, not the injury and not lodging the claim. Everything about damages flows from that document and the DPI on it.
- The 20% DPI is the line, and you have 20 business days. Below 20% DPI, you elect between the lump sum and damages irrevocably. At or above it, you can do both, with the lump sum deducted under the terms set out in s 270. Silence is a deferral, but your payments stop regardless.
- The 3 years runs from when the cause of action arose, and Schedule 5 can extend it where a notice of assessment lands late. Dust-related conditions have no limit at all.
Get help now
If you have a notice of assessment in front of you, it’s a great idea to have a professional read the DPI figure and the offer before the 20 business days run out.
Call 1800 960 482 or enquire online to have someone at Smiths’ Lawyers take a look at your case under our No Win, No Fee, No Catch® promise.
We will explain what your DPI figure means, what your deadlines are and whether there is a negligence claim worth looking at. You can also use the form below for a free case review.